
- Choose the correct income period
- ITR-1: a simplified form with important exclusions
- ITR-2 and ITR-3: check business income first
- ITR-4: presumptive eligibility is only the first test
Choose a return form from the full set of your circumstances, not from the largest income source alone. Salary does not automatically mean ITR-1, and a small business does not automatically qualify for ITR-4. Review the notified form for the assessment year because eligibility and schedules can change between years.
Choose the correct income period
For income earned from 1 April 2025 to 31 March 2026, select Assessment Year (AY) 2026-27 and apply the Income-tax Act, 1961. Income earned from 1 April 2026 belongs to Tax Year 2026-27 under the Income-tax Act, 2025. These are different periods. A return or notice about an earlier year does not move to the new Act merely because you handle it after April 2026.
ITR-1: a simplified form with important exclusions
For AY 2026-27, ITR-1 is intended for eligible resident individuals other than residents not ordinarily resident, within the prescribed income ceiling and permitted sources. The notified form now accommodates up to two house properties. Eligibility remains restricted by other conditions, including business income, short-term capital gains, certain foreign matters, directorship and other exclusions. Check the specific limited section 112A capital-gain allowance rather than assuming every capital gain is permitted.
ITR-2 and ITR-3: check business income first
ITR-2 is generally for individuals and HUFs without business or professional income who cannot use ITR-1. ITR-3 covers individuals and HUFs with relevant business or professional income and wider schedules. Investments, trading activity and receipts from a partnership require proper classification. A taxpayer should not force a transaction into another income head merely to keep using a simpler return.
ITR-4: presumptive eligibility is only the first test
ITR-4 is an optional simplified return for eligible resident individuals, HUFs and firms other than LLPs with qualifying presumptive income and within the form’s limits. The business or profession must qualify for its presumptive provision, and the form’s separate exclusions must also be checked. A receipts ceiling for presumptive taxation does not mean the ITR-4 total-income ceiling disappears. Use its current name, not the obsolete ITR-4S label.
ITR-5, ITR-6 and ITR-7: identify the legal person
ITR-5 covers eligible persons such as firms, LLPs and certain other entities, subject to its exclusions. ITR-6 is generally used by companies other than those claiming exemption under section 11. ITR-7 applies to persons required to furnish returns under the specified provisions, including relevant charitable or religious entities and institutions. Merely calling an organisation an NGO does not establish which form or exemption applies.
Check the utility and every necessary schedule
Use the official assessment-year download or portal utility and answer its eligibility questions accurately. Identify capital gains, foreign assets, house property, business accounts, deductions, tax credits and loss schedules before submission. A portal wizard assists selection but depends on truthful inputs. If the chosen form cannot report a required item, revisit form eligibility rather than leaving the item out.
Practical checklist
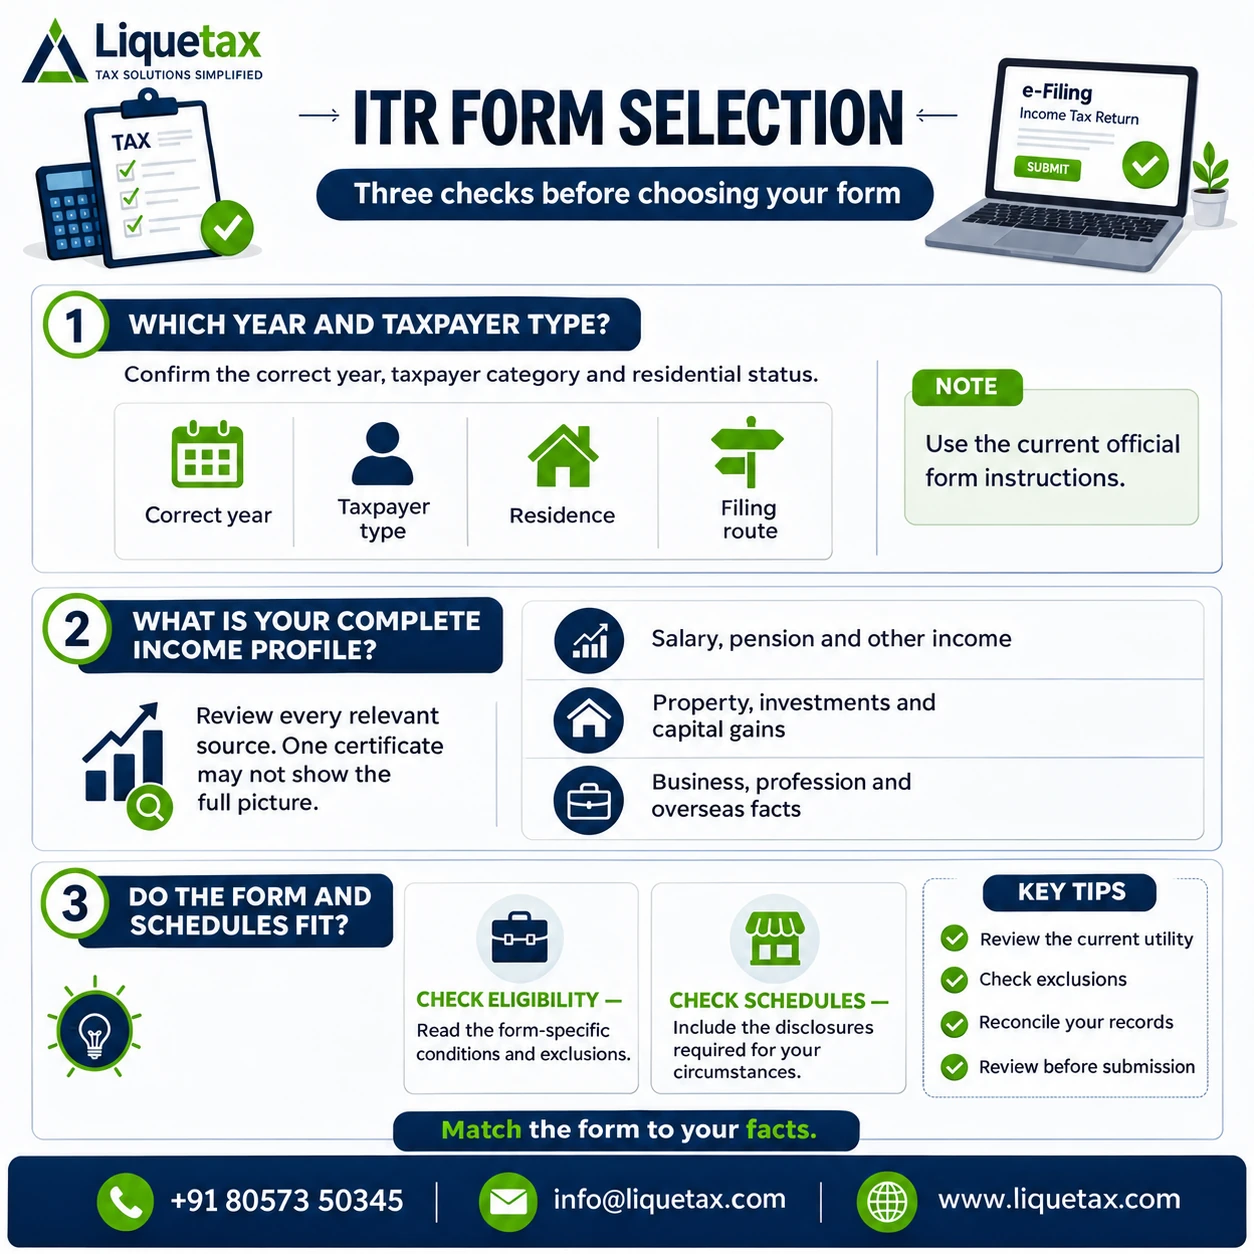
- Confirm the legal taxpayer: individual, HUF, firm, LLP, company or other entity.
- Determine residential status for the year using the relevant rules.
- List every income source, asset disclosure, loss and special circumstance.
- Check presumptive eligibility and form exclusions as separate tests.
- Use the current notified form and retain the final return with all schedules.
Worked example
Illustration: an employee receives salary and sells investments producing a short-term capital gain. The salary alone might suggest a simple return, but that gain can make ITR-1 unsuitable. The taxpayer evaluates ITR-2 if there is no business income, while an actual business or professional activity could require ITR-3. The form follows the facts; it should never determine which facts the taxpayer chooses to report.
Frequently asked questions
Does one salary certificate prove ITR-1 eligibility?
No. Residency, other income, assets and exclusions must also be checked.
Can an LLP use ITR-4?
No. LLPs are excluded from that simplified form even where their activity is relatively small.
Are two house properties automatically disqualifying in AY 2026-27?
The notified ITR-1 now accommodates up to two, but all other eligibility conditions and loss-related requirements still matter.
Is presumptive taxation the same as ITR-4?
No. It is a computation method; ITR-4 has its own taxpayer, income and exclusion conditions.
What if the wrong form was already filed?
Review available revision or defect-response procedures for the year and circumstances promptly. Do not ignore a resulting notice.
Official references
- Income Tax Department: current return forms and utilities
- Notification 45/2026: notified ITR-1
- Income Tax Department: AY 2026-27 salary tax guidance
- Income Tax Department: current return obligations and deadlines
For help reviewing your documents and the correct next step, contact LIQUETAX. The scope and any professional fee should be agreed in writing after the facts are checked. This article provides general information; individual eligibility depends on the applicable law and records.