
- Choose the correct income period
- Authenticate the notice and select the year
- Distinguish section 139(9) from processing
- Handle scrutiny and reassessment deliberately
An income-tax communication may ask for verification, propose an adjustment, report processing, require documents or begin a different proceeding. The section number and actual wording matter more than an alarming subject line. Authenticate the document, preserve it and identify the response route before deciding whether tax is due or a correction is needed.
Choose the correct income period
For income earned from 1 April 2025 to 31 March 2026, select Assessment Year (AY) 2026-27 and apply the Income-tax Act, 1961. Income earned from 1 April 2026 belongs to Tax Year 2026-27 under the Income-tax Act, 2025. These are different periods. A return or notice about an earlier year does not move to the new Act merely because you handle it after April 2026.
Authenticate the notice and select the year
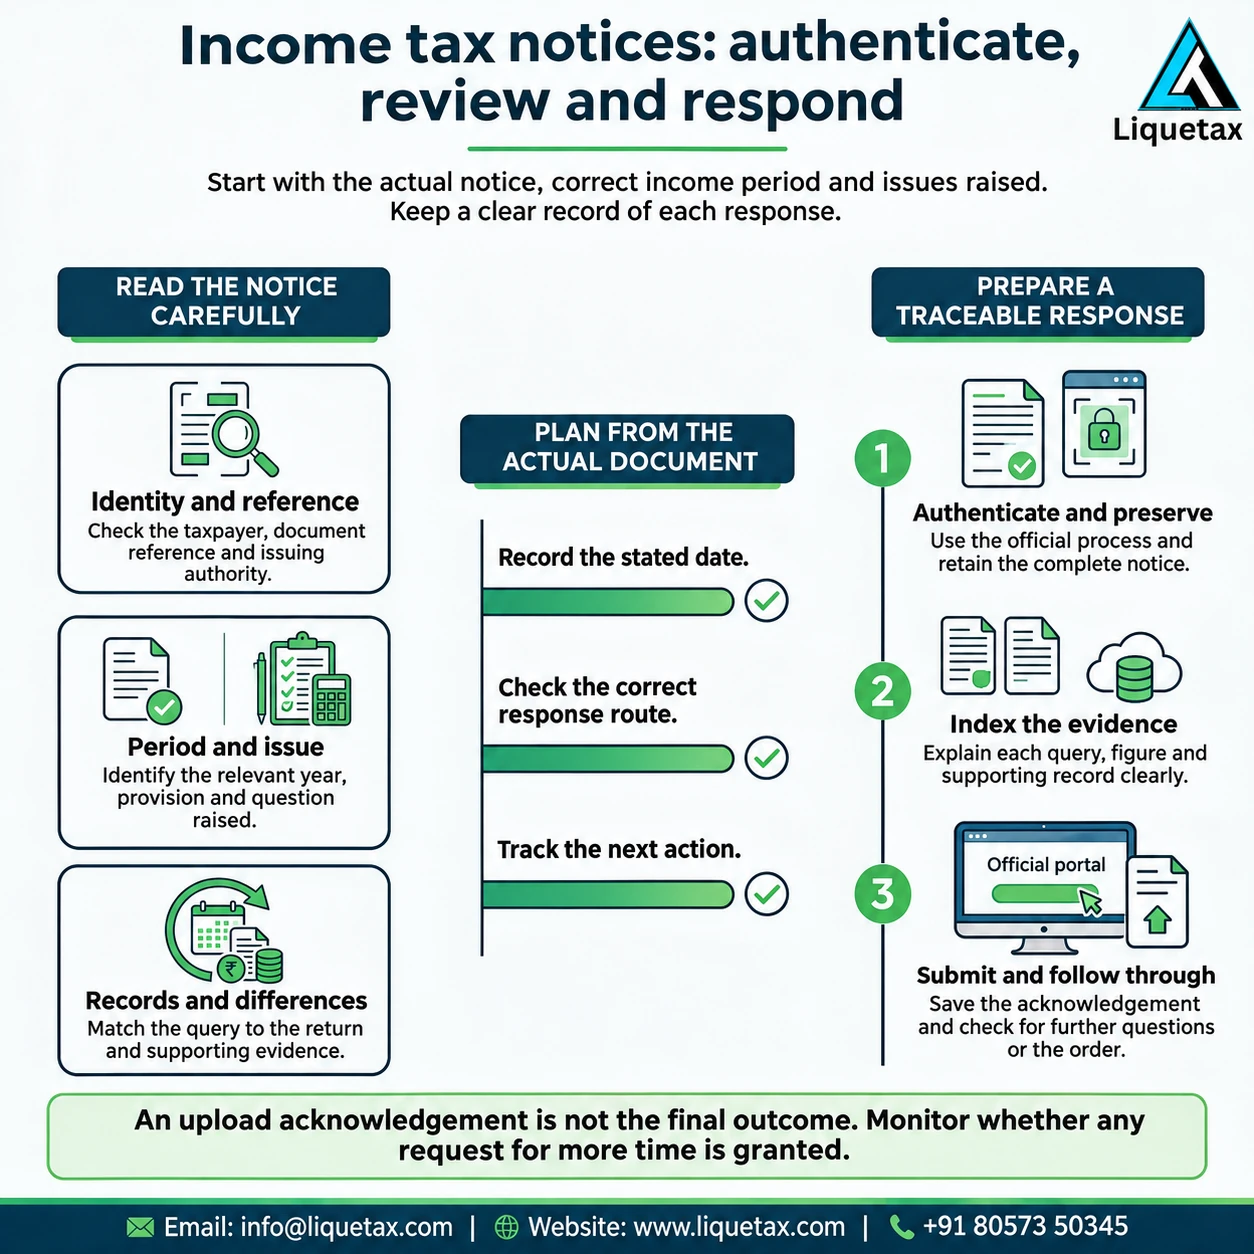
Use the official e-filing portal’s notice-authentication service and inspect your account independently. Check PAN, assessment year, DIN or other reference, issue date, service information and response deadline. Save all pages and attachments. A refund-related SMS is not a complete notice. Do not share credentials or make payment through an unsolicited link claiming that a refund will otherwise expire.
Distinguish section 139(9) from processing
A defective-return notice under section 139(9) identifies a defect and provides an opportunity to rectify it within the permitted period. Read the defect code and submit the required correction through its response mechanism. An intimation under section 143(1) instead sets out processing results; a proposed adjustment may invite a prior response. Neither should be treated as identical to a full scrutiny assessment.
Handle scrutiny and reassessment deliberately
A section 143(2) notice can initiate scrutiny, while sections 148A and 148 concern reassessment procedures for the relevant years. Their requirements, time limits and available objections are fact-dependent. Read the complete communication and accompanying material. An old sample letter cannot establish that a notice is valid or invalid. Material reassessment or jurisdiction issues deserve professional review before submission.
Prepare an evidence table
For each query, state the return figure, the Department’s figure, the difference and the supporting record. Salary matters may need employer certificates; tax-credit differences need Form 26AS, TDS certificates and deductor follow-up; asset transactions need cost and sale evidence. Explain reconciliation and timing differences clearly. Avoid sending an unindexed collection of bank statements without showing which entries answer the question.
Submit through the correct process and track the outcome
Use the portal service indicated in the notice, attach readable indexed evidence and retain the acknowledgement. Request more time where necessary through the proper facility, but monitor whether it is granted. A grievance does not replace a response, rectification or appeal. After submission, check for further questions and read the eventual intimation or order; a successful upload alone does not settle the dispute.
Practical checklist
- Authenticate the document and save the complete notice and attachments.
- Record the relevant year, legal section, deadline and hearing details.
- Compare the allegation with the filed return and original records.
- Prepare a numbered reply and annexure index answering each issue.
- Save submission evidence and monitor the next communication.
Worked example
Illustration: a return claims TDS that does not appear in the Department’s processing calculation. The taxpayer compares Form 26AS and the employer certificate, discovers a reporting error and asks the employer to correct it. The taxpayer also responds to the actual communication within the allowed time. Correcting the employer’s statement and responding to the notice are related tasks, but one does not automatically replace the other.
Frequently asked questions
Is every notice a demand for payment?
No. It may seek information, identify a defect or propose an adjustment. Read the operative part of the document.
Can I respond only by email?
Use the required statutory or portal response route. An informal email may not count as compliance.
Does a refund notice prove fraud?
No. A claim may be checked for mismatches or supporting evidence without establishing wrongdoing.
Which law applies to an old-year notice received in 2026?
AY 2026-27 and earlier proceedings remain governed by the 1961 Act under the transition rules. Check the year and provision.
Can I wait until a deductor corrects TDS?
Do not miss the notice deadline while waiting. Explain the situation with evidence and seek appropriate time if needed.
Official references
- Income Tax Department: notice authentication and responses
- Income Tax Department: transition and return FAQs
- Income Tax Department: current return obligations and deadlines
For help reviewing your documents and the correct next step, View income tax notice reply support contact LIQUETAX. The scope and any professional fee should be agreed in writing after the facts are checked. This article provides general information; individual eligibility depends on the applicable law and records.