
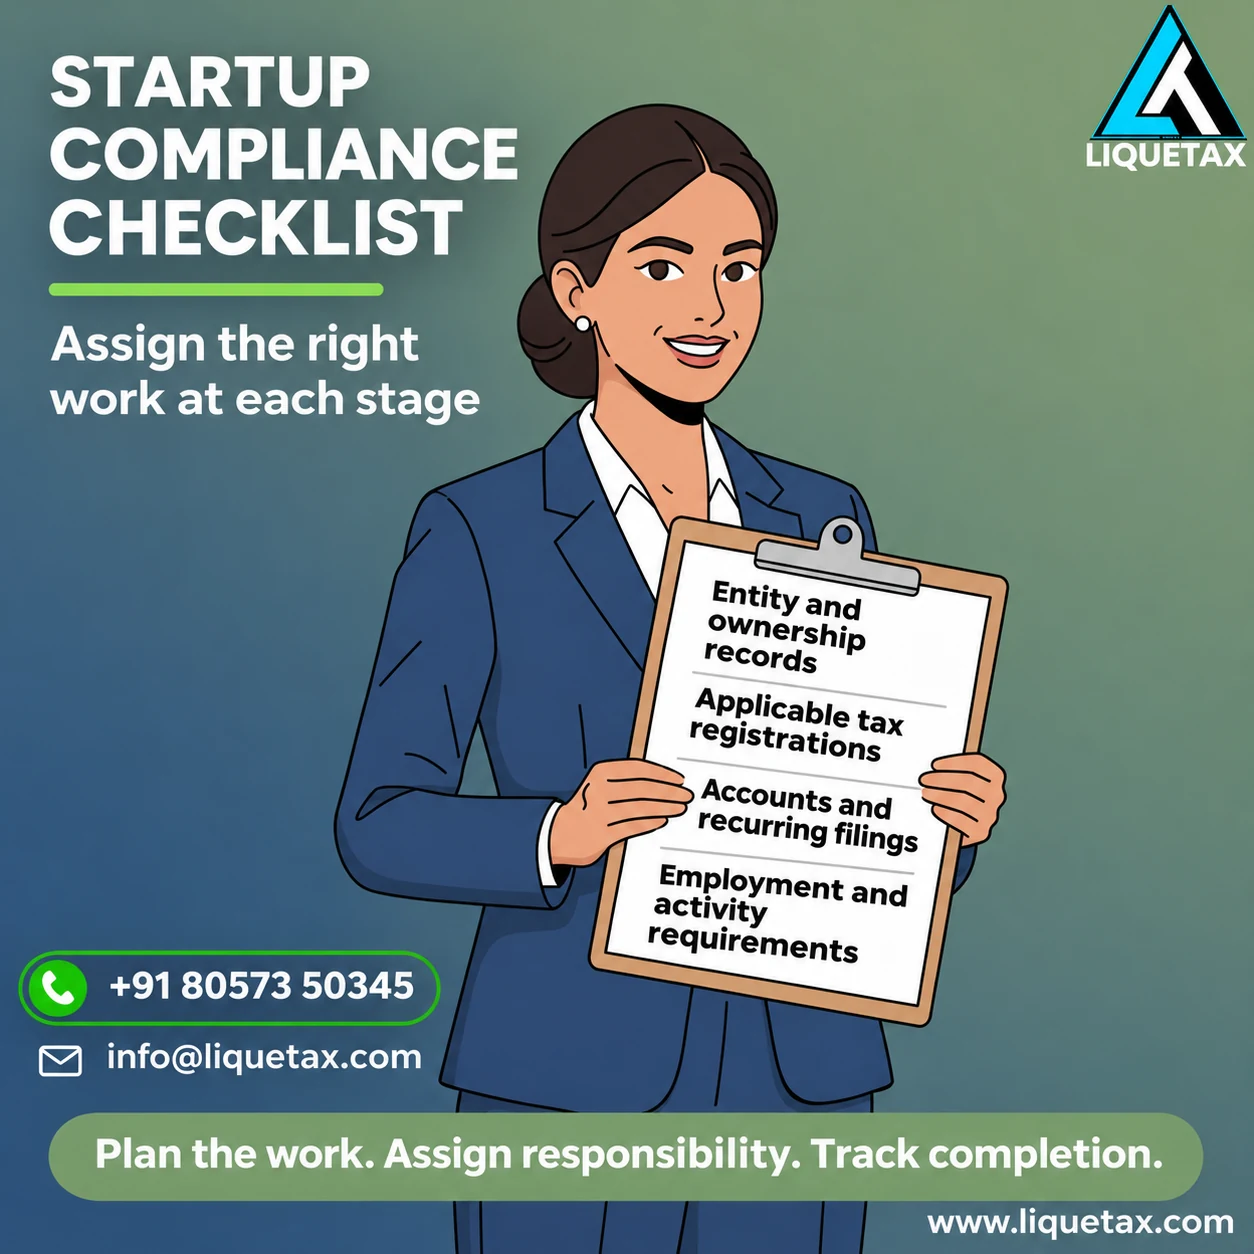
- 1. Plan ownership
Agree structure, roles and business activity.
- 2. Prepare launch
Check applicable tax and product requirements.
- 3. Run the routine
Maintain records and authorise filings.
- 4. Review growth
Recheck new people, locations and investment.
Before launch: clarify ownership and the business model
Choose a structure using ownership, liability, funding and continuing compliance. Record how founders will contribute money, time and intellectual property. Resolve signing authority and key decisions before contracts are entered into or accounts are created.
Write down the product, customer, premises and selling channel. This description supports tax, local and sector-specific reviews. Do not assume that every startup needs every certificate or that incorporation settles the permissions for a regulated product.
At launch: connect registrations to actual requirements
Review GST applicability, relevant licences and business banking. Use consistent legal names and contact details across documents. Track application references, clarification requests and granted certificates separately so that your team can report the real status.
If you plan to use a brand, assess name and trademark risks before paying for packaging and advertising. If you seek DPIIT recognition, check current eligibility and maintain genuine evidence of the innovation or scalable model. Recognition does not automatically provide funding or a tax holiday.
During operations: make the records repeatable
Set a monthly process for invoices, expenses, purchase evidence, bank entries and payroll where relevant. Record cancellations, refunds and stock movements clearly. A founder should know what the business earned, what it owes and which documents explain the figures.
For each filing, define who gathers records, who prepares them, who approves the submission and who retains the acknowledgement. Keep exceptions visible. Missing invoices, unpaid liabilities and unanswered portal notices should not disappear into an email thread labelled 'done'.
When hiring: review the actual employment arrangements
Prepare suitable employment or contractor documents, confidentiality terms and intellectual-property arrangements. Describe the relationship accurately; calling someone a consultant does not settle every employment question. Employee numbers, wages, location and activity can trigger further statutory reviews.
Keep payroll and personnel records organised, including joining and exit information. Ask which labour, social-security or workplace obligations apply to the business's facts. The relevant state and framework matter, so a checklist copied from a different business may miss the required action.
Before growth: review what is changing
New investment, directors, a branch, an export channel or a regulated product may require decisions and filings before the change goes live. Keep the transaction documents and dates together so that the reviewer can identify the relevant route.
Revisit the compliance register each quarter and when a major event occurs. Close completed actions with evidence and carry pending items forward with an owner and date. The aim is a manageable operating habit that supports decisions, rather than a large checklist nobody maintains.
A practical startup compliance register
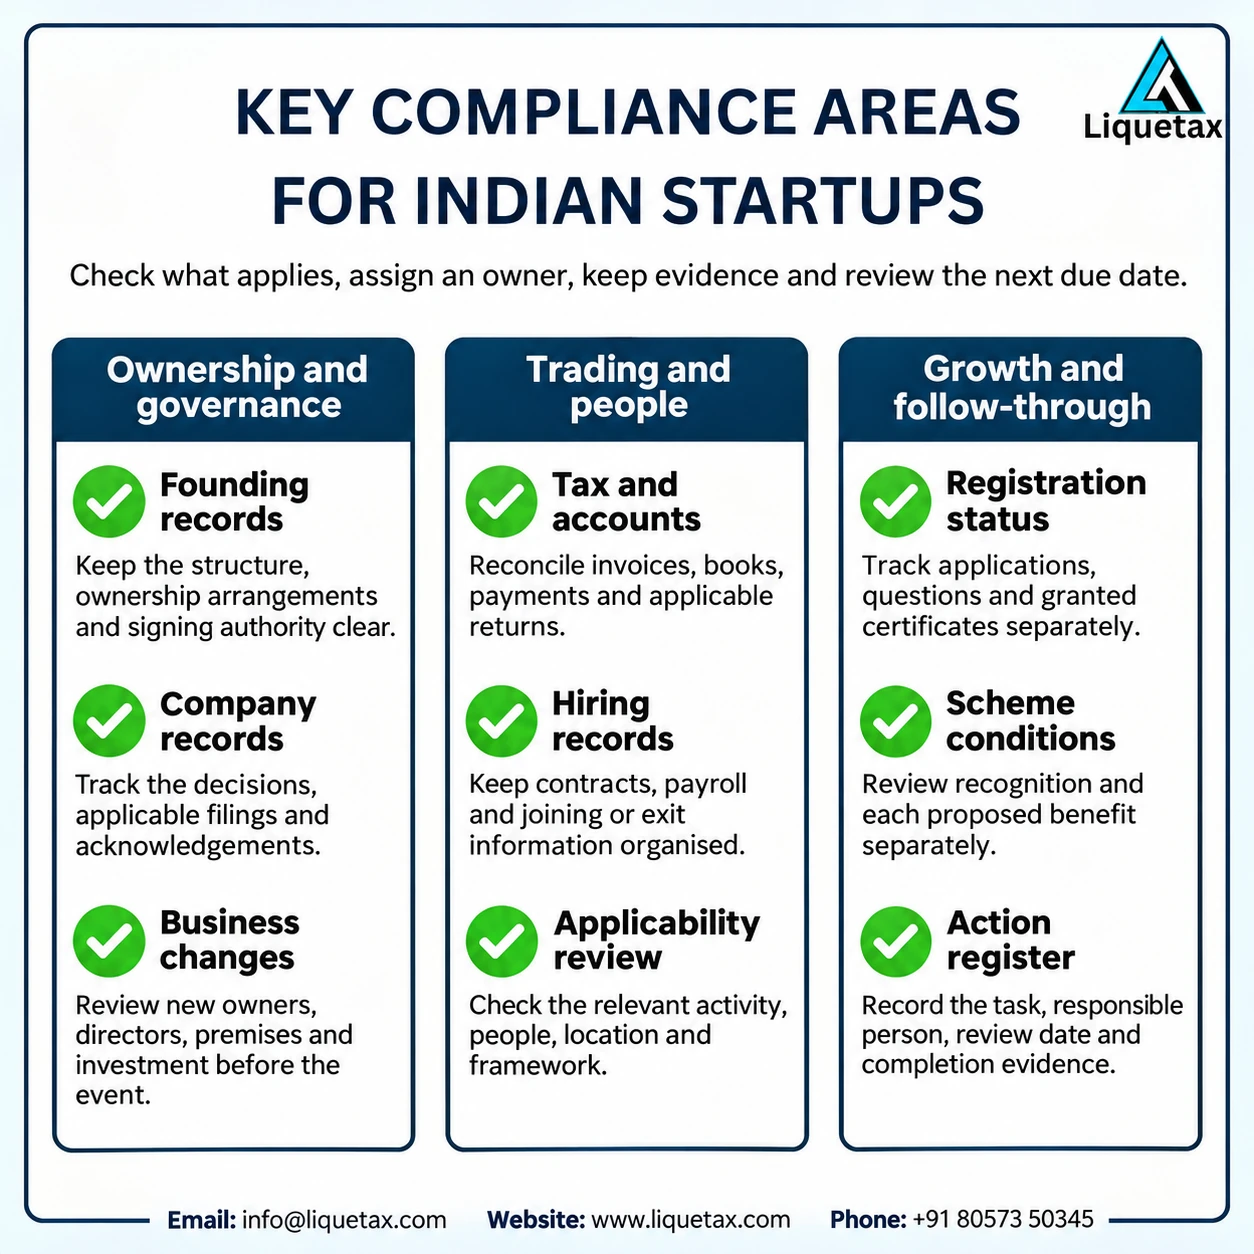
| Stage | Record and responsibility |
|---|---|
| Founding | Structure, ownership agreement and signing authority. |
| Launch | Tax, product, premises and bank requirements. |
| Trading | Invoices, books, settlements and applicable returns. |
| Hiring | Contracts, payroll and statutory applicability. |
| Growth | Event approvals, investment and updated records. |
Illustrative example
Illustrative example: a software startup begins with two founders and later hires a team and accepts an overseas investor. Its initial checklist should be updated for employment and foreign-investment questions. Keeping the incorporation folder alone would not address the new obligations.
Frequently asked questions
Is this the same checklist for every startup?
No. Use it to organise questions; apply the rules that match your structure, activity, state and stage.
Does Startup India recognition replace incorporation?
No. Entity creation and DPIIT recognition are separate processes with different requirements.
Will recognition guarantee funding or tax relief?
No. Each funding or tax route has separate eligibility, application and approval conditions.
Who should own the compliance register?
Nominate an internal coordinator and assign each preparation, approval and evidence-retention task to a responsible person.
When should the plan change?
Update it when ownership, employees, premises, products, customer channels or applicable rules change.
Get clarity before your next filing
Bring the records listed above to a LIQUETAX conversation. Ask for the applicable work, documents, responsibilities and fee components in writing before you authorise a submission. Government charges, professional fees and applicable GST should be shown separately.
Book a conversationOfficial references
- Companies Act, 2013: India Code
- Startup India: official recognition and schemes
- GSTN: normal taxpayer registration guide
Check the linked authority for the rule, form and notification that applies to your facts and period. This guide explains preparation and does not record a professional opinion on an individual case.