
- 1. Describe activity
Explain owners, products and locations.
- 2. Review requirements
Separate mandatory work and optional choices.
- 3. Prepare records
Match evidence to the applicable route.
- 4. Plan continuing work
Retain status and future responsibilities.
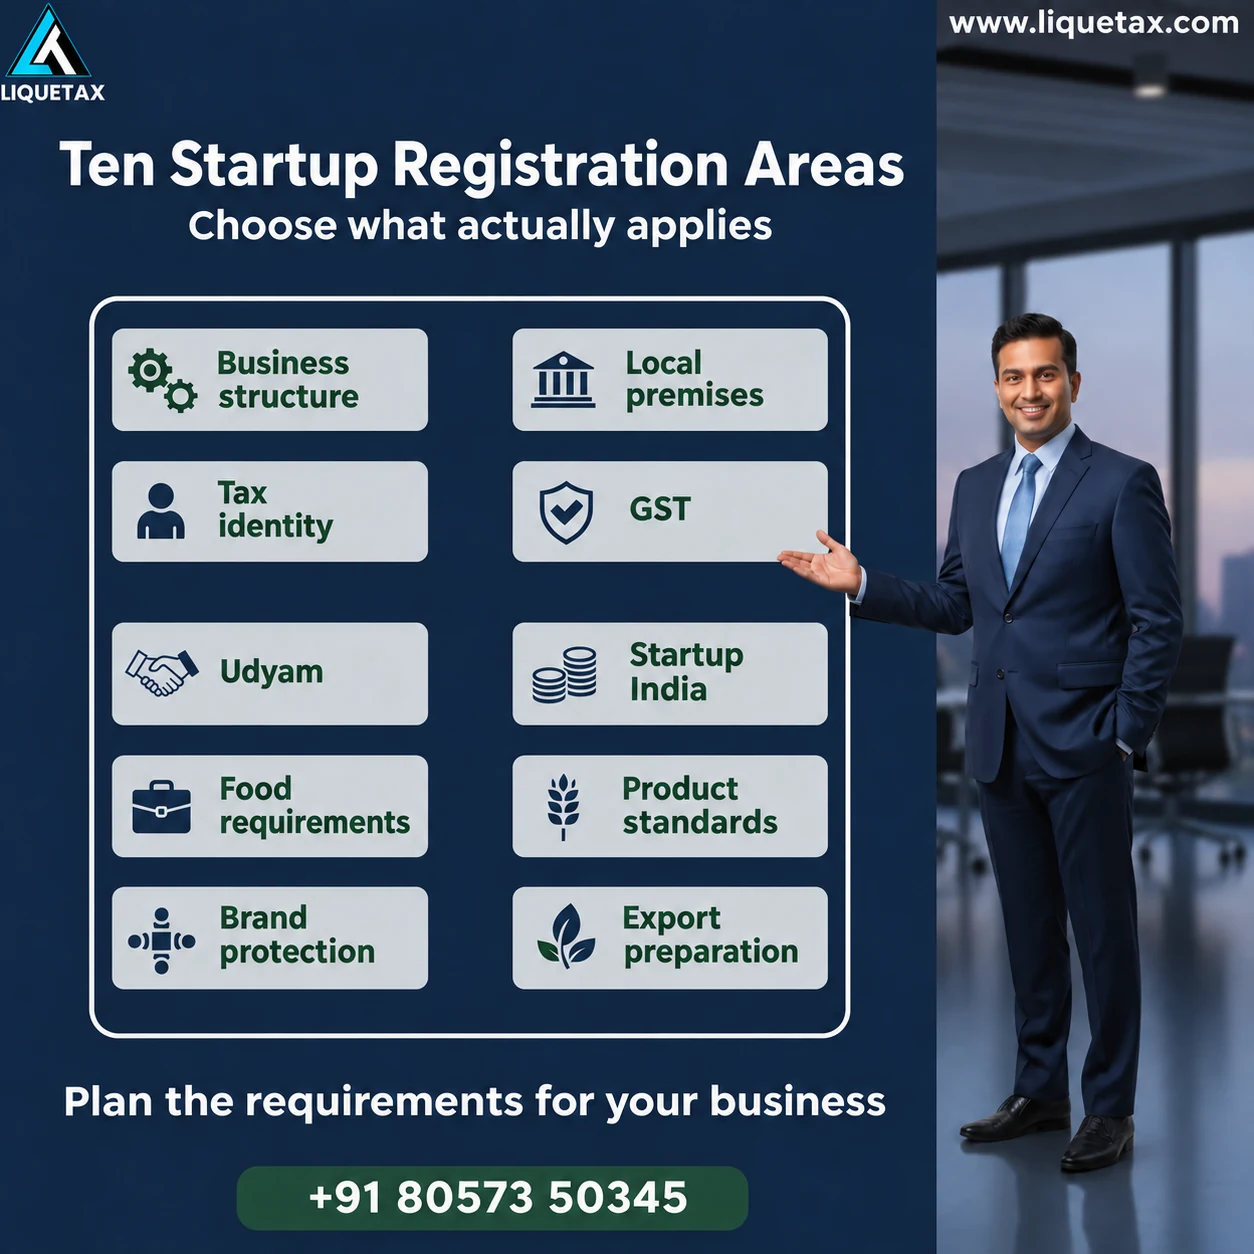
1–2. Business structure and local premises
Compare proprietorship, partnership, LLP and company structures using ownership, liability, investment and continuing compliance. A company is not automatically the best choice for every small business. Record the reason for the chosen form and the actual owner or partner arrangements.
Local premises and Shops and Establishments requirements should be reviewed using the state, activity and actual workplace. A certificate obtained in one system does not replace local or sector permissions. Explain additional operating locations before assuming the registered office covers everything.
3–4. Tax identity and GST
PAN and any relevant TAN requirement have distinct purposes. Review the actual entity and withholding obligations rather than buying every tax identifier without a reason. Keep names and contact records consistent.
GST needs its own activity, turnover, state and transaction review. Registration liability, taxpayer category and input-credit eligibility are different questions. Once a suitable registration route is confirmed, plan invoices, books and applicable returns as well as the initial application.
5–6. Udyam and Startup India recognition
Udyam's official government process is free. It can support relevant MSME eligibility checks, but does not guarantee a loan or tender award. Any optional paid record-preparation work should be identified separately.
DPIIT recognition has current entity, activity and category conditions. It is separate from incorporation and from tax or funding approval. Check the revised framework and genuine business evidence before making an application or promising a benefit.
7–8. Food and other product requirements
For a food business, use the current FSSAI framework and FoSCoS instructions. The 2026 reform raised turnover thresholds from April: registration up to ₹1.5 crore, state licensing up to ₹50 crore and central licensing above that level. Activity and special-category conditions still need checking.
Other regulated products can require different licences, testing or standards. Identify the manufacturer, importer, packer and seller roles. A GSTIN or company certificate does not authorise every product, and a turnover-only decision can miss a category-specific requirement.
9–10. Brand protection and export preparation
Trademark clearance and registration concern the actual brand, owner and goods or services. A domain or company-name approval is not a universal brand clearance. Review rights before committing to packaging or advertising.
For overseas sales, review the actual trade, product, destination, banking and tax conditions. IEC requirements and exemptions need the correct goods or services analysis. Udyam and Startup India recognition are not substitutes for the documents required for an export transaction.
Turn the list into an action register
For each proposed item, record whether it is required now, optional, dependent on another action or awaiting facts. Note the source, preparation records, government charges, professional fees and applicable GST. Assign responsibility for the work after registration.
Review the register when the startup hires people, raises funds, adds a state, changes products or enters a new channel. The useful outcome is a clear plan based on real requirements, not the largest possible collection of certificates.
Registration decision register
| Area | Decision to record |
|---|---|
| Structure and premises | Ownership form and actual location requirements. |
| Tax | Identity, withholding, GST and filing responsibilities. |
| Enterprise programmes | Udyam/recognition eligibility and separate benefits. |
| Product | Current licences, standards and operating roles. |
| Brand and export | Rights and transaction-specific requirements. |
Illustrative example
Illustrative example: a home-food business selling locally may need a different set of reviews from a software company seeking investment. Both should choose registrations from their actual activity and stage instead of purchasing the same generic package.
Frequently asked questions
Are all ten areas mandatory for every startup?
No. Use the list to identify questions, then apply the requirements that fit your business.
Is the old ₹12-lakh FSSAI headline current?
Use the revised 2026 framework and current category instructions, not a recycled old threshold.
Do certificates guarantee loans or government orders?
No. Each lender, scheme and procurement opportunity has separate conditions.
Can a tax registration replace a product licence?
No. Review the product and operating role independently.
What should a quote show?
The actual required work, scope, responsibilities and separately identified government charges, professional fees and GST.
Get clarity before your next filing
Bring the records listed above to a LIQUETAX conversation. Ask for the applicable work, documents, responsibilities and fee components in writing before you authorise a submission. Government charges, professional fees and applicable GST should be shown separately.
Book a conversationOfficial references
- Companies Act, 2013: India Code
- FSSAI reform and turnover thresholds
- Official Udyam registration portal
- Startup India: official recognition and schemes
- DGFT: Foreign Trade Policy, revised chapter 2
Check the linked authority for the rule, form and notification that applies to your facts and period. This guide explains preparation and does not record a professional opinion on an individual case.