
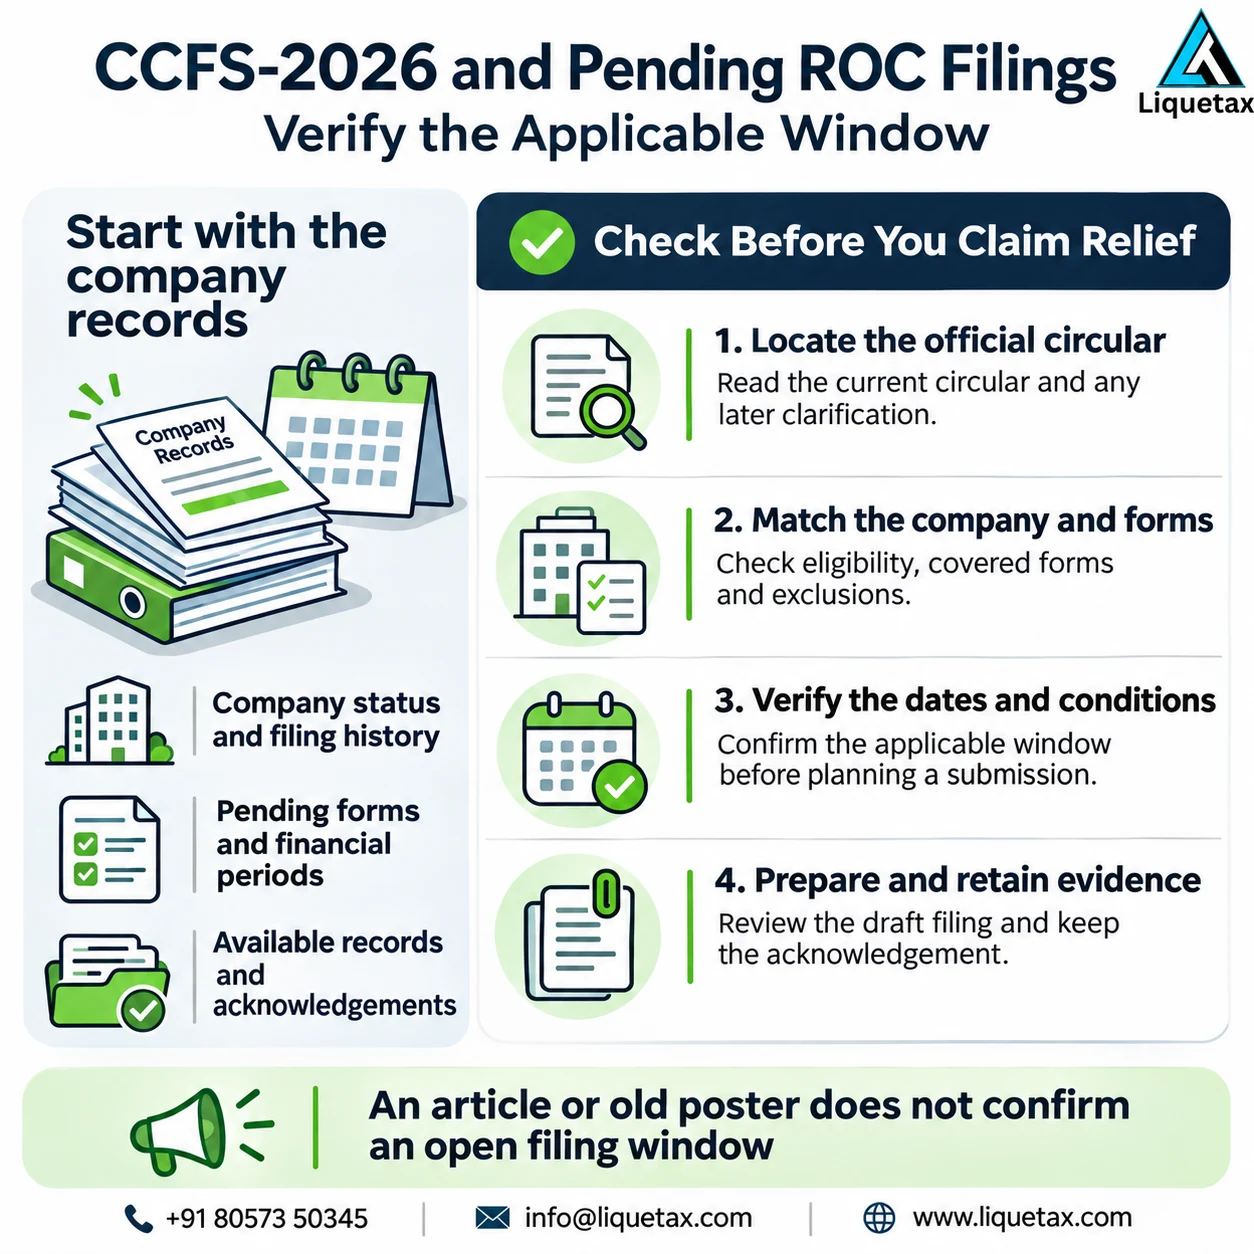
- 1. Find the source
Use the actual scheme and later circulars.
- 2. Check the date
Check the SRN date against 15 September 2026.
- 3. Review the company
Check forms, status and proceedings.
- 4. Prepare the action
Approve accurate records and keep evidence.
When did the CCFS-2026 extension end?
If you are holding an old quotation that mentions CCFS, check its date against the filing acknowledgement. An estimate raised in August could have assumed a concession that was unavailable when the company filed in October.
Read MCA General Circular 04/2026, dated 31 August 2026 (PDF).
| MCA circular | Effect |
|---|---|
| 01/2026 · 24 February 2026 | Opened on 15 April 2026 with an initial end date of 15 July. |
| 03/2026 · 8 July 2026 | Moved the last date to 31 August 2026. |
| 04/2026 · 31 August 2026 | Extended the scheme through 15 September 2026. |
What did the scheme actually reduce?
Eligible companies could pay the normal filing fee plus 10% of the applicable additional fee on specified outstanding forms. For example, if the additional fee on an eligible filing was ₹20,000, its scheme component was ₹2,000. That calculation excluded the normal fee and any professional charges. It was available during the filing window.
The original scheme also allowed eligible applications for dormant status at half the applicable application fee, or for strike-off at a quarter of the applicable fee. Those were separate choices with distinct eligibility requirements. A reduced application fee did not settle debts, finalise accounts or establish a right to close a company.
How do I check a filing made during the scheme?
Match the CIN and financial year on the filed form with the service request number (SRN), receipt and filing date. Keep the normal and additional fee amounts. For an eligibility review, check whether the Registrar had already issued a final strike-off notice, whether the company had applied for strike-off or applied for dormant status before the scheme began, and whether it was dissolved through amalgamation or classed as vanishing.
A penalty order needs its own review. For defaults under sections 92 and 137, the scheme identified filings before an adjudication notice or within 30 days of that notice. An existing penalty order or a later filing outside that notice window has a different consequence. Keep the complete notice, service date and order with the receipt.
Prepare genuine records before submitting
A concession does not remove the need for accurate accounts, meeting records, declarations and attachments. List gaps and dependencies before choosing a filing date. Do not invent documents or backdate events simply to make a pending period appear complete.
Review the correct form, entity, period and authorised signatory. Agree the submission in writing and retain the approved version. A professional quote should distinguish government charges, preparation fees and applicable GST so that you know what is being paid.
What can I do about a pending ROC filing after 15 September?
First list the year and the missing form. If the firm has already filed its financial statements, obtain the AOC-4 reference and ask whether the annual return for that same period is still open. Agree a price for the missing return and any necessary review of earlier records.
For FY 2025–26, MCA Circular 05/2026 offers separate additional-fee relief for covered AOC-4 forms through 31 December 2026 and for MGT-7 or MGT-7A through 31 January 2027. It applies to those forms for that year. Check your dates in the ROC compliance calendar.
Scheme-source and company review
| Check | Evidence needed |
|---|---|
| Scheme and amendment | Official title, circular number and text. |
| Relevant window | Dates applicable to the intended filing. |
| Company eligibility | Status and applicable exclusions. |
| Forms and proceedings | Pending periods, notices and orders. |
| Authorised action | Accurate records, fee basis and acknowledgement. |
Two late returns can have different costs
Illustrative Workflow Example
Consider a director clearing two years in November 2026. The missing FY 2024–25 annual return needs a current fee estimate. The FY 2025–26 annual return may still qualify for that year’s separate relief. A single “backlog package” can hide the difference. Ask for two lines, each naming the year, form, fee paid to MCA and professional charge.
Frequently asked questions
What was the last date for CCFS-2026?
MCA Circular 04/2026 extended the window through 15 September 2026. The original July and intermediate August dates were superseded.
Can a November 2026 filing use the CCFS discount?
The scheme window closed in September. Check the filing year and any separate circular that specifically covers that form.
Was the total filing fee reduced to 10%?
For covered overdue forms, the concession applied to the additional fee. Normal filing fees were payable separately.
Does filing under the scheme cancel a penalty order?
An existing adjudication order requires separate review. Keep the notice, issue date, order and form acknowledgement together.
Can I get a quote for just one overdue return?
Yes. Give the company type, financial year and the filing reference for the completed form. Ask the adviser to identify the outstanding return and the work included.
Need to regularise filings from several years?
List each outstanding form against its financial year. Flag any active notice or resubmission first so its response date is visible when you request the quote.
Ask for the cost of the work still open
A form-by-form review can reveal a completed filing that the new adviser would otherwise prepare again. Reconstructing a missing year can add time and cost, especially if signed accounts or registers are missing. Identify those gaps before agreeing a submission date. Get an itemised ROC annual filing service quote for the year concerned.