
- Define purposeExplain the funding need.
- Prepare recordsReconcile cash flow and evidence.
- Lender reviewCredit decision and terms.
- Track outcomeSanction conditions and disbursement.
An MSME certificate can help describe your enterprise, but a lender still needs to assess the proposal. Start with what the money will fund, how it will be repaid and what the business records show. Prepare a credible application rather than treating collateral-free finance as an automatic reward for registration.
Separate enterprise registration, lending and guarantee cover
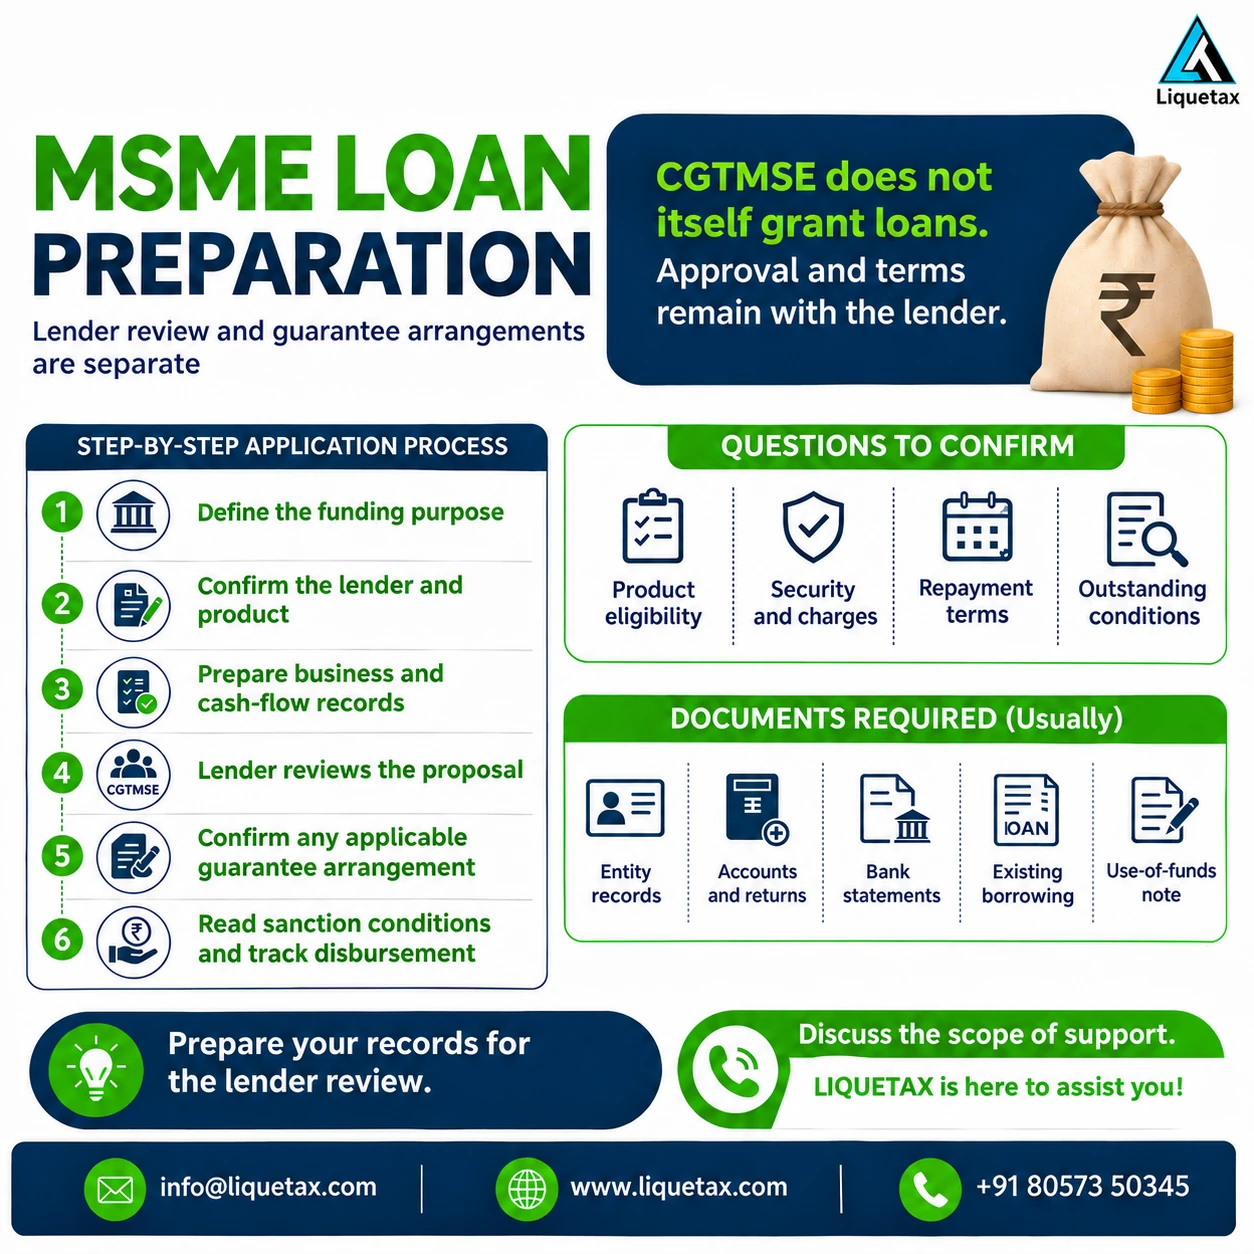
Udyam records enterprise information; it is not a loan sanction. CGTMSE explains that it provides guarantees to member lending institutions and does not itself grant loans or appoint agents to arrange them. Eligible borrowers approach a participating lender with their proposal. The lender’s credit decision and the applicable guarantee arrangement are different stages, so a certificate or adviser’s application pack cannot promise approval.
Describe the use of funds in one page
State whether you need machinery, stock, working capital or another business purpose. Explain the amount you seek, the operating problem it addresses and the expected cash-flow effect. Distinguish an estimate from an existing order or signed contract. A small manufacturer purchasing equipment should keep the supplier quotation with its production plan; a trader seeking working capital should explain inventory and customer-payment cycles.
Organise records that explain repayment
Prepare the business identity and registration records, relevant tax returns, accounts, bank statements, existing borrowing details and the lender’s requested information. Reconcile important differences before submission. If the books show sales that do not match receipts, provide a clear explanation instead of altering records to create an attractive picture. A forecast should identify assumptions and remain distinct from historical results.
Discuss security and charges with the lender
Ask which product is being considered, what eligibility and documentation apply, and whether guarantee cover is proposed. Get the security position, interest basis, fees, repayment schedule and conditions in writing. Do not assume that the phrase collateral-free means no primary-security arrangement, no personal obligations or no cost. CGTMSE’s official material distinguishes security concepts and products; the actual sanction documents need an individual review.
Compare affordability before accepting an offer
Build a monthly view of expected receipts, operating payments, tax commitments and debt instalments. Test a slower-payment scenario rather than relying only on the most optimistic sales plan. Identify how the business would handle a temporary shortfall. These are practical planning suggestions, not a lender’s assessment or a personalised finance recommendation. Ask a qualified adviser to review a material borrowing commitment and unclear conditions.
Use LIQUETAX for a defined preparation task
Discuss the record organisation, bookkeeping reconciliation, proposal preparation and coordination you need. Ask for a written scope and itemised professional fee. Identify which lender communications and follow-up are included, and retain control of your application and authorisations. LIQUETAX should not be described as a CGTMSE-appointed agent or the decision-maker. No engagement should promise a loan, a subsidy or a particular sanction date.
Know what counts as completion
A prepared proposal, an application acknowledgement, a sanction letter and disbursement are different outcomes. Keep the document for the stage actually reached and list any outstanding conditions. Check the sanctioned terms before acceptance and retain the repayment obligations after disbursement. Assign someone to track lender requests and the business records needed later. A useful handover makes the remaining actions clear even if the loan is not sanctioned.
Questions before you act
Does my Udyam certificate guarantee collateral-free funding?
No. The enterprise record, lender’s credit decision and any guarantee arrangement are separate. Confirm the product and terms with the lender.
Can I pay an adviser to obtain a CGTMSE loan directly?
CGTMSE states that it does not grant loans or appoint loan-arranging agents. Ask any adviser to explain its own preparation service accurately; approach the participating lender for credit.
Official references and their limits
- CGTMSE: official home and warning
Guarantees to member lenders; no direct lending or appointed loan-arranging agents.
Official search-visible content checked on 11 October 2026; direct page timed out.
- CGTMSE: borrowers and member lending institutions
Borrowers approach participating banks or institutions with proposals.
Official indexed FAQ checked; no lender account or application inspected.
- CGTMSE: security distinctions
Primary security, collateral and guarantee distinctions.
Official indexed content checked; current sanction terms require individual review.
Useful next steps
Discuss your requirement with LIQUETAXAI-assisted educational writing by LIQUETAX Editorial. No named professional endorsement or individual outcome is claimed.