
- Map the liability before applying
- Understand Maharashtra PTRC and PTEC
- Check Maharashtra rates, exemptions and periodicity
- Use Karnataka’s current portal and schedule
Professional tax is governed by the applicable state law, not by a single national salary table. Maharashtra and Karnataka both require attention to the person liable, employment location, schedule entry and exemptions. Employer payroll compliance and a business’s own enrolment can be separate obligations. A GST registration or company incorporation does not settle every professional-tax requirement.
Map the liability before applying
Identify the entity, business activity, commencement date, offices and employee work locations. Check whether the state schedule covers the business or professional and whether employer deduction obligations arise. Do not assume registration starts only with 20 employees. Likewise, a person with no employees may need enrolment under a relevant schedule entry even though there is no payroll deduction obligation.
Understand Maharashtra PTRC and PTEC
PTRC concerns an employer’s responsibility to deduct and remit tax on covered salary or wage payments. PTEC concerns enrolment and tax liability of persons covered by the schedule. A business may need one or both depending on facts. Use the state’s prescribed registration forms and instructions. Each certificate should be linked to the correct legal person and liability date, rather than copied from another group company.
Check Maharashtra rates, exemptions and periodicity
The applicable salary category and exemptions matter, including changes affecting women employees and other exempt groups. The state publishes current schedules, notifications and annual return periodicity. Do not use a uniform ₹7,500 professional-tax rate: the constitutional annual ceiling is ₹2,500 per person, while the applicable charge still depends on state law. Review the particular payroll month and any special collection pattern rather than dividing a guessed annual amount equally.
Use Karnataka’s current portal and schedule
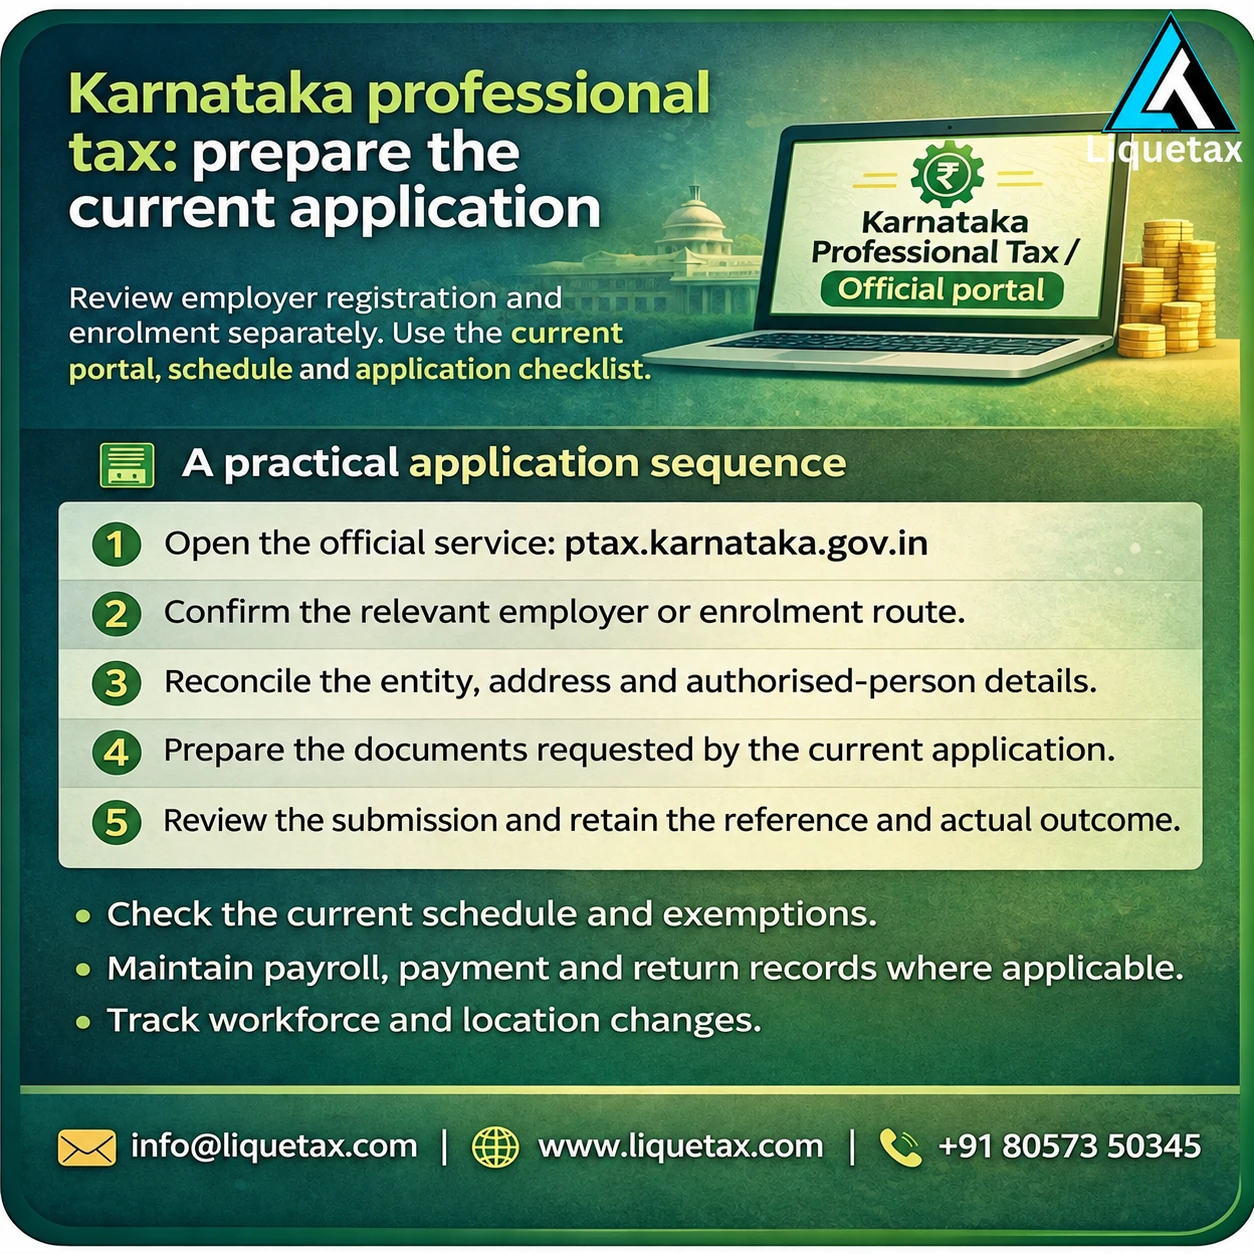
Karnataka’s profession-tax service is at the official ptax.karnataka.gov.in portal. The older pt.kar.nic.in address directs users to the updated service. Review employer registration and enrolment separately and use the currently applicable salary threshold, exemptions and payment calendar. The historic ₹15,000/₹20,000 salary table should not be reused as current guidance. If the service or notification is unclear, obtain clarification before deducting an unsupported amount.
Prepare an application and payroll control file
Keep PAN, entity constitution, address and authorised-person evidence, business details and employee salary records ready. Check the precise documents requested by the current application. After registration, reconcile employee-wise deductions with the payroll register, payments and returns. Retain exemption evidence where claimed, and track joiners, leavers and location changes. A certificate without ongoing payment and filing controls is incomplete compliance.
Check live service notices without assuming relief
Maharashtra has issued 2026 notices about registration and return facilities and relaxation. A past temporary relaxation is not an indefinite exemption. Check the exact period, conditions and latest communication before relying on it. Preserve any service ticket and evidence of an unavailable facility, but separately assess payment and filing duties. Use official payment channels and save challans against the right registration and period.
Practical checklist
- Identify employer registration and entity or professional enrolment separately.
- Confirm the state schedule entry, employee category and exemption evidence.
- Gather PAN, constitution, address and authorisation documents.
- Check current portal notices, deadlines and return periodicity.
- Reconcile payroll deductions, challans and filed returns every period.
Worked example
Illustration: a consulting LLP opens an office and hires one employee. It should examine its own enrolment position and the employer obligation based on that employee’s pay and state rules. Waiting for a 20-person workforce may be incorrect. If a second office opens in another state, the first certificate cannot simply be treated as nationwide coverage; the new state’s rules and actual work arrangements require a separate review.
Frequently asked questions
Are PTRC and PTEC the same?
No. Maharashtra uses them for different obligations: employer payroll compliance and enrolment under the applicable schedule.
Is there one India-wide salary slab?
No. Apply the relevant state’s legislation, current schedule and exemptions.
Does no payroll mean no professional tax?
Not necessarily. The business or professional may separately fall within an enrolment category.
Can I rely on an old portal-relaxation notice?
Only if its dates and conditions cover the current obligation. Check later official notices before relying on relief.
What evidence should payroll retain?
Keep salary records, category and exemption evidence, deduction workings, payment challans and return acknowledgements.
Official references
- Maharashtra: profession tax registration instructions
- Maharashtra: profession tax notifications
- Karnataka: official profession tax portal
For help reviewing your documents and the correct next step, contact LIQUETAX. The scope and any professional fee should be agreed in writing after the facts are checked. This article provides general information; individual eligibility depends on the applicable law and records.