
- Locate the relevant state and schedule entry
- Separate employer registration and enrolment
- Check exemptions and the actual amount
- Prepare consistent application documents
Professional tax is a state-level levy on covered professions, trades, callings and employment. It is not the same as income tax, GST or a professional qualification. Whether you need to register depends on the state law, legal person, activity and employment facts. Start by mapping the obligation before opening an online application.
Locate the relevant state and schedule entry
Identify where the business operates and where employees work, including branches and significant changes in work arrangements. Check whether the relevant state imposes the levy and how its schedule applies to your category. States can use different thresholds, exemptions and procedures. A consultant should not assume that the rules for a salaried employee or a business in another state apply unchanged.
Separate employer registration and enrolment
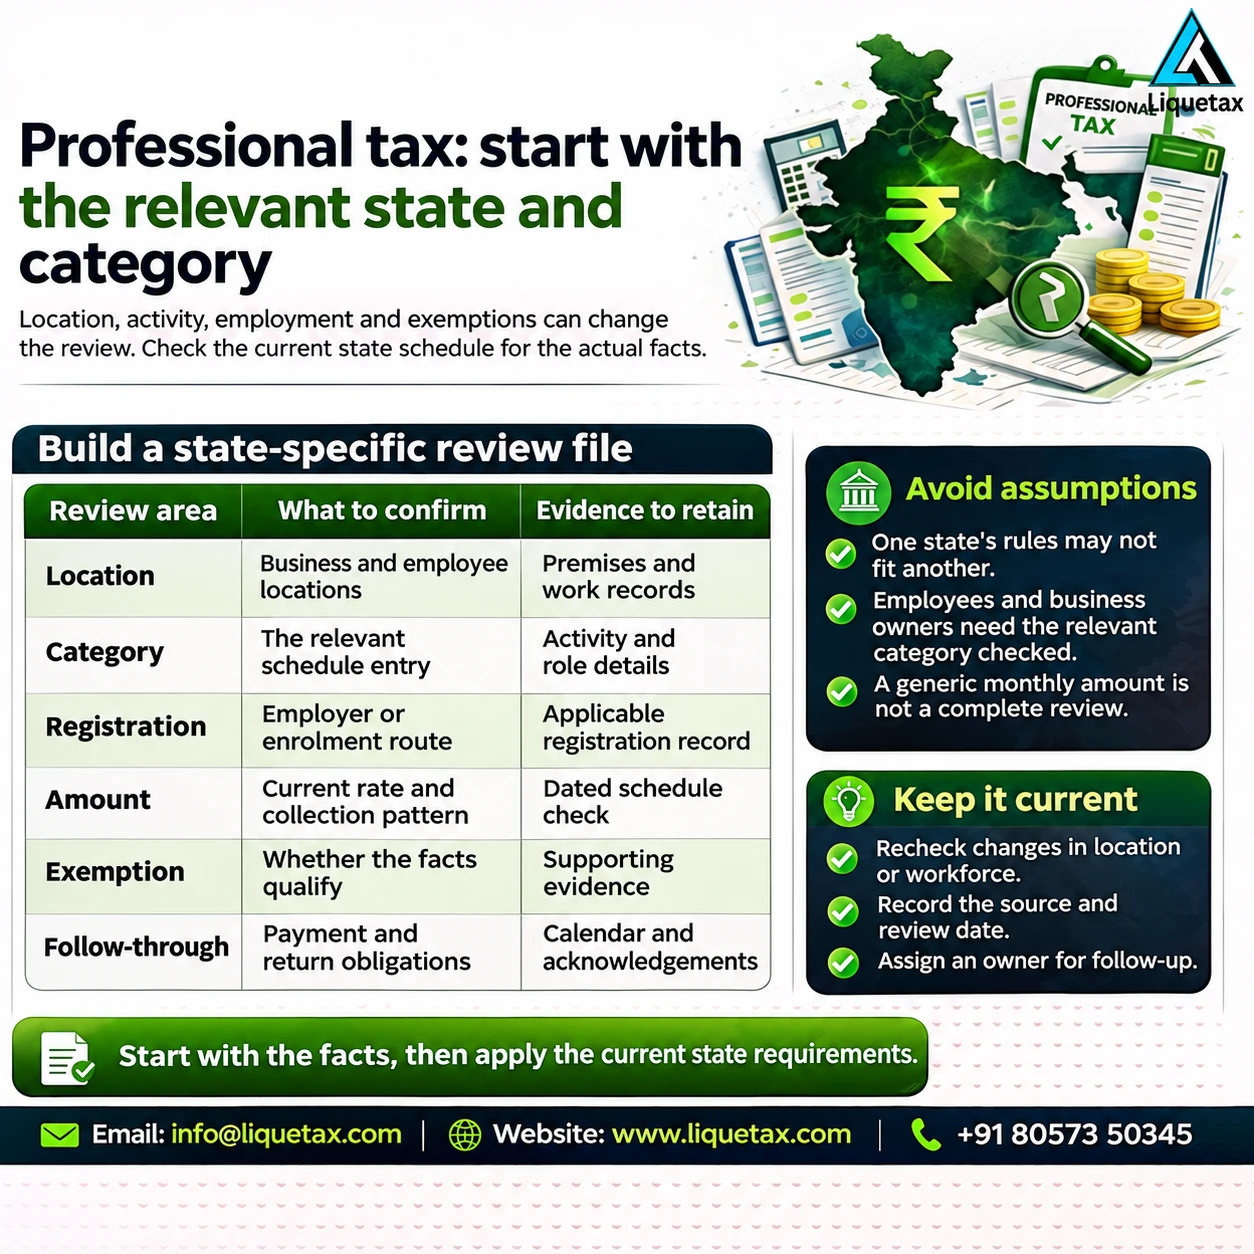
An employer may need to deduct and remit tax on covered salary payments. Separately, a professional, entity or business may owe tax under an enrolment category. Maharashtra uses the familiar PTRC and PTEC distinction, while other states have their own terminology and workflow. Having no employees may remove a payroll task without removing every enrolment obligation. A single employee can require checking employer duties.
Check exemptions and the actual amount
The constitutional annual ceiling is ₹2,500 per person, but the applicable state schedule determines the actual charge and collection pattern. Exemptions can depend on person, employment or other statutory facts. Obtain evidence before marking someone exempt. Avoid broad statements that every employee pays the same monthly amount or that every proprietor, director and partner has identical liability in every state.
Prepare consistent application documents
Keep PAN, constitution documents, business address evidence, authorised-person details and relevant employment or activity information ready. The portal may request additional documents for the category. Use the true commencement or liability date rather than an arbitrary current date. Review any existing registration before applying again: a duplicate certificate can complicate payments and records rather than cure a mismatch.
Plan payment, return and record obligations
After registration or enrolment, record the applicable payment and filing cycle and any certificate conditions. Reconcile employee-wise deductions with payroll, payment challans and returns. Handle changes in salaries, exemptions, branches and legal constitution promptly under the state procedure. Preserve the evidence behind each decision. Registration alone does not complete the recurring compliance work.
Handle changes, closure and portal issues deliberately
Where a business stops or changes location, check the amendment or cancellation process and settle the relevant earlier obligations. Do not simply stop payroll deductions or returns without reviewing legal status. For portal problems, use official help channels and retain the service ticket. A technical error or historic temporary relaxation should not be treated as a permanent exemption from tax or filing duties.
Practical checklist
- Identify each relevant state, legal person and category of activity.
- Assess employer registration and separate enrolment obligations.
- Check current slabs, exemptions, periodicity and commencement dates.
- Prepare identity, constitution, premises and authorisation evidence.
- Create a reconciliation and calendar covering payroll, payments and returns.
Worked example
Illustration: an individual consultant starts employing an assistant. The consultant’s own enrolment position and the assistant’s salary-based deduction position are two separate questions. The consultant checks the state schedule, salary threshold and employer procedure rather than assuming that an existing GSTIN covers both. When the assistant later moves to a different work location, the state-law implications are reviewed again instead of blindly retaining the old payroll setting.
Frequently asked questions
Is professional tax the same as a professional licence?
No. Payment or registration does not authorise a regulated profession or replace a professional qualification.
Does a GSTIN replace professional-tax registration?
No. The obligations arise under different laws and must be assessed separately.
Are rates identical across India?
No. State schedules, exemptions and collection patterns differ within the constitutional ceiling.
Can a business without employees need enrolment?
Yes, depending on the state schedule and the person’s category. Payroll and enrolment are separate tests.
What should I do after registration?
Record the recurring payment and filing duties, maintain supporting evidence and reconcile them with payroll and accounts.
Official references
- Maharashtra: profession tax registration instructions
- Maharashtra: profession tax notifications
- Karnataka: official profession tax portal
For help reviewing your documents and the correct next step, contact LIQUETAX. The scope and any professional fee should be agreed in writing after the facts are checked. This article provides general information; individual eligibility depends on the applicable law and records.