File with a clear picture of your income, tax records and next steps. LIQUETAX coordinates income tax return preparation for individuals and businesses, with qualified professionals engaged where required. Start with the relevant year, income sources and filing status to agree the records, work and fee.
Quote after scope reviewProfessional fee GST & external charges extra
Individuals, professionals and business owners seeking a clear filing scope. Tell us if the matter involves an entity return, capital transactions, foreign income, losses, a missed filing or a notice so it can be assessed separately.
Work to agree
Agree the year, taxpayer and income categories covered
Review supplied records and relevant tax-credit information
Not included: Guaranteed tax savings, refund amount or refund date
Fee basis
Quote after scope review
Professional fee. Applicable GST, government charges and agreed third-party costs are extra.
One specified service engagement. Confirm the applicant, deliverables and exclusions in writing before work starts.
Records to prepare
Taxpayer category, relevant year and previous-return details
Property income and relevant loan records
Start with a brief description. Share private records only through the agreed channel after the checklist is confirmed.
Which financial year or assessment year needs attention?
What are the main income sources?
What is the current filing status?
Pan-India support
Review before filing
Written scope & pricing
One team, clear next steps
YOUR REQUIREMENT, CLEARLY DEFINED
A filing scope that matches your income
Salary, investments, freelance receipts and company accounts need different preparation. The correct return depends on the full taxpayer profile and the rules for the relevant year.
Salary or pension: include other income such as interest, rent and capital transactions
Freelancers and proprietors: describe the activity, receipts, expenses and available books
Companies and other entities: identify accounts readiness and any required professional review
Flag overseas income or assets, residency questions, losses and earlier filings at the start
Choose the correct filing period
AY 2026–27 and Tax Year 2026–27 refer to different income periods. Income earned in FY 2025–26 is associated with AY 2026–27 under the Income-tax Act, 1961. Income earned from 1 April 2026 to 31 March 2027 falls in Tax Year 2026–27 under the Income-tax Act, 2025.
Confirm the income period before selecting a return or making a payment
Keep earlier-period references and applicable form rules with the correct year
Review deadlines, available filing routes and regime choices for your facts
Ask for a separate assessment if a return is missed, incorrect or already under enquiry
Reconcile your records before filing
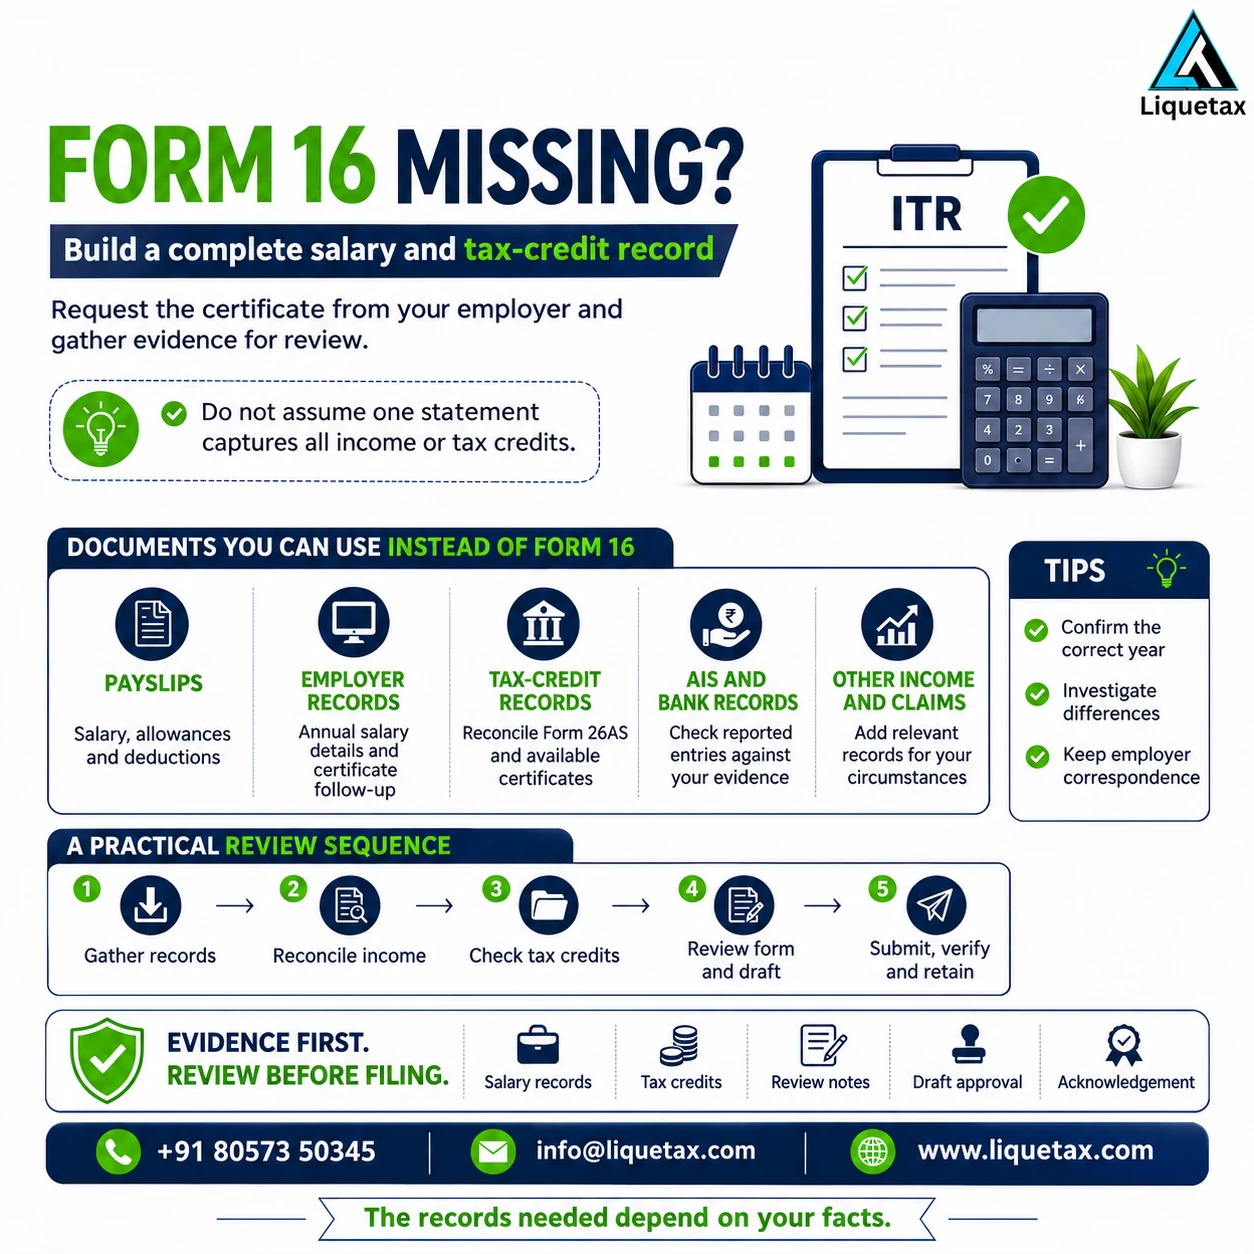
Form 16 and prefilled information are starting points. Compare the income and tax-credit records with your own statements so material gaps can be resolved before submission.
Form 16 or 16A where applicable, AIS and Form 26AS
Bank interest, property income, investment transactions and relevant supporting records
Business books, receipts and expenses for business or professional income
Evidence for any deduction, relief or loss being considered; retain the supporting documents
Review, submit and complete verification
Agree who prepares the computation, who approves the figures and how verification will be completed. Ask for the acknowledgement, computation and any follow-up actions at handover.
Review income, tax credits and payment requirements before authorising the return
Complete the applicable verification step promptly; uploading alone does not finish the process
Keep professional fees separate from tax, statutory interest and late-filing amounts
Confirm whether bookkeeping, audit, notices, corrections or refund follow-up need a separate scope
An electronic certificate used to authenticate a person’s digital signature. A licensed Certifying Authority issues it after the required identity checks. Official reference →
BUILT AROUND YOUR BUSINESS
Less uncertainty. More direction.
Individuals, professionals and business owners seeking a clear filing scope. Tell us if the matter involves an entity return, capital transactions, foreign income, losses, a missed filing or a notice so it can be assessed separately.
Clarity before commitment
Know the deliverables, documents and costs before work starts.
Careful preparation
Identify missing or inconsistent information before submission.
Coordinated support
Bring preparation, queries and follow-up into one agreed workflow.
Practical next steps
Know what you need to provide and what happens at handover.
WATCH & UNDERSTAND
Documents Required for Income Tax Return Filing in India
Use the video to organise your records, then follow the checklist agreed for your taxpayer type and year.
Watch the topic explained, then use the written service guide and its current checklist to prepare your next step. Rules and figures in a recording may change.
We’ll share an applicant-specific checklist after a short discussion. The exact records depend on your circumstances.
01
Starting records
Taxpayer category, relevant year and previous-return details
Relevant Form 16/16A, AIS and Form 26AS
Bank interest, other income and tax-payment records
Bank-account details required for the filing/refund workflow
02
Income-dependent documents
Property income and relevant loan records
Broker statements and acquisition/sale workings for capital transactions
Books, receipts and expense records for business/profession
Evidence supporting any eligible deduction or relief being considered
03
Special situations
Foreign-income/assets and residential-status records
Prior losses and previous-return computations
Earlier filed return, acknowledgement and notices for a correction or response scope
If Form 16 is unavailable, request it from your employer and prepare salary, tax-credit and other relevant records for reconciliation.View graphic at full size ↗Check your document readiness
Before your first conversation
A useful start. No phone number needed.
Organise your business facts and get a checklist to discuss with our team.
Read the short guide
First, describe your business and the result you need. Next, organise the relevant facts without sharing private documents here. Finally, review your checklist with the team and agree the written scope before work starts.
Audio uses your browser’s available voice. The same information is provided as text.
We prepare, coordinate and track the agreed work. You stay involved in the decisions that matter.
01
Identify the filing
Confirm the year, taxpayer profile and proposed work.
02
Reconcile and prepare
Review the supplied records and document material differences.
03
Approve and submit
Explain the proposed return and payment position within the engagement.
04
Verify and track
Coordinate verification and share the available filing records.
Timing agreed after document review
Preparation is agreed after the income profile and records are checked. Filing deadlines, extensions and verification requirements must be checked for the relevant year and route. Department processing and refunds are outside LIQUETAX's control.
KNOW EXACTLY WHERE YOU STAND
Clear scope. No surprises.
The written engagement confirms your deliverables and costs before work starts.
Service scope to agree
Agree the year, taxpayer and income categories covered
Review supplied records and relevant tax-credit information
Identify missing facts and prepare the agreed computation and return
Obtain approval before submission and coordinate the permitted verification method
Hand over the acknowledgement, computation and follow-up list
Outside the standard scope
—Guaranteed tax savings, refund amount or refund date
—Invented deductions or omission of reportable income
—Audit, notice replies, appeals or foreign-tax advice unless separately agreed
—Every correction, updated return or historic year under one unspecified fee
No. Eligibility depends on the relevant year's form rules and the person's full facts. Capital transactions, residential status, overseas assets or other income can change the answer.
The Department's AY 2026-27 FAQ excludes income from business or profession from ITR-2. The appropriate form must be selected from the complete taxpayer profile.
No. Complete the applicable verification/ITR-V step. The Department's cited FAQ states 30 days from filing; delay can change the furnishing date and bring applicable late-filing consequences.
No refund is guaranteed. Any claim depends on the return facts and the Department's processing. A professional fee does not purchase a particular tax outcome.
Which year does this guidance cover?+
The ITR-2 form-specific reference covers AY 2026–27, associated with FY 2025–26 income. The separate Tax Year 2026–27 starts on 1 April 2026 under the Income-tax Act, 2025. This guide does not transfer form eligibility, section references or deadlines between those periods. Confirm the income period and applicable rules at intake.
Can I share my tax files by WhatsApp immediately?+
Start with the service, year and broad income categories. Agree a secure document channel first; do not put PAN, Aadhaar, OTPs or full tax records in a general enquiry.
Do you provide income tax return filing services for companies and businesses?+
Yes. Share the entity type, relevant income period, income sources and accounts status. The team will confirm the records and professional involvement needed. Accounting, audit and other separate services should be expressly listed in the engagement.
Is Form 16 enough to prepare my income tax return?+
Not always. Other income, capital transactions, deductions and tax credits can require additional records. Compare Form 16 with AIS, Form 26AS and relevant bank, investment or business statements rather than assuming one certificate covers the entire return.
Are AY 2026–27 and Tax Year 2026–27 the same?+
No. AY 2026–27 concerns income from FY 2025–26 under the Income-tax Act, 1961. Tax Year 2026–27 concerns income earned from 1 April 2026 to 31 March 2027 under the Income-tax Act, 2025. Confirm the income period and applicable Act before choosing the filing or payment option.
Is income-tax refund assistance the same as return filing?+
No. Preparing and verifying a return is different from reviewing a pending, adjusted or failed refund. Identify the recorded filing and processing stage so the team can confirm the appropriate work. A refund amount or payment date is not guaranteed.
THINK ONE STEP AHEAD
Keep your business moving.
Connect this service with your next milestone.
THE DETAIL, WHEN YOU NEED IT
Explore the full service guide.
Who this service helps & key decisions
File with a clear picture of your income, tax records and next steps. LIQUETAX coordinates income tax return preparation for individuals and businesses, with qualified professionals engaged where required. Start with the relevant year, income sources and filing status to agree the records, work and fee.
Individuals, professionals and business owners seeking a clear filing scope. Tell us if the matter involves an entity return, capital transactions, foreign income, losses, a missed filing or a notice so it can be assessed separately.
Question
What matters
Next step
Year and route
AY 2026–27 covers FY 2025–26 income under the 1961 Act; Tax Year 2026–27 covers income from 1 April 2026 under the 2025 Act.
Confirm the income period, applicable law and permitted filing route before choosing the form.
Income profile
Salary, property, capital transactions and business income can change the form and schedules.
Disclose every material income source before selecting a form.
Residence and overseas facts
Foreign income, assets and residential status can require a different review.
Flag them at intake rather than after preparation.
Tax-credit records
Compare relevant income evidence, AIS and Form 26AS.
Investigate omissions and differences; prefilled data is not a substitute for records.
Verification
For the covered electronically filed returns, the Department states a 30-day verification/ITR-V period.
Track the actual deadline and completion status; upload alone is not the final check.
Fee details, estimates & quote variables
Quote after scope review. Professional fee. Applicable GST, government charges and agreed third-party costs are extra.
One specified service engagement. Confirm the applicant, deliverables and exclusions in writing before work starts.
Professional fees and applicable GST are separate from income tax, interest and statutory late-filing or additional amounts where applicable. These depend on the year, facts and filing route. No refund-based or all-inclusive statutory amount is promised here.
Year and taxpayer type
Number and complexity of income sources
Capital transactions, business books or overseas facts
Original filing versus a separately assessed correction, backlog or notice
Preparation is agreed after the income profile and records are checked. Filing deadlines, extensions and verification requirements must be checked for the relevant year and route. Department processing and refunds are outside LIQUETAX's control.
Your responsibilities, handover & ongoing work
Identify the filing
LIQUETAX: Confirm the year, taxpayer profile and proposed work.
You: Disclose all income types, residence facts and any existing filing or notice.
Reconcile and prepare
LIQUETAX: Review the supplied records and document material differences.
You: Provide missing evidence and answer the fact questions before computation.
Approve and submit
LIQUETAX: Explain the proposed return and payment position within the engagement.
You: Approve the facts, arrange required payments and authorise submission.
Verify and track
LIQUETAX: Coordinate verification and share the available filing records.
You: Complete the authorised verification method and monitor later communications.
At handover and afterwards
Retain the computation and acknowledgement
Confirm the verification status and relevant completion date
Monitor processing, refund-bank status and notices
Have differences or omissions assessed before choosing a correction route
Common mistakes to avoid
Selecting a form only because it was used last year
Missing bank interest, capital transactions or overseas facts
Treating AIS or Form 26AS as the whole income record
Submitting without resolving material differences
Forgetting verification or ignoring later communications
Official references & source-check information
Source-checked educational guide. AI-assisted source research checked on . No named professional endorsement is claimed. Confirm current requirements for your facts before filing. Next review target: 2026-12-15.
Distinguishes AY 2026–27 and earlier periods under the 1961 Act from Tax Year 2026–27 onwards under the 2025 Act.
Official FAQ checked on 15 November 2026 for the filing-period explanation. This is separate from the earlier source-check date for other guide content.
Supporting records, AIS and Form 26AS reconciliation, appropriate return selection and retaining evidence for annexure-less returns.
Official preparation guidance checked on 15 November 2026. Using this checklist does not establish eligibility for ITR-1.
Last updated: . This records the educational content date; it does not establish an individual professional review.
Disclaimer: this guide provides educational information and does not replace individual professional advice. Confirm your facts, current official requirements and written engagement before acting.
LET’S TAKE THE NEXT STEP
Ready to get started?
Let’s discuss your income tax return filing and prepare a scope that fits.