
- 1. Establish the facts
Identify the family and relevant ownership.
- 2. Trace assets
Record how property or funds arose.
- 3. Check tax treatment
Review clubbing and the correct period.
- 4. Keep records
Separate genuine HUF and personal activity.
Separate the family structure from a tax estimate
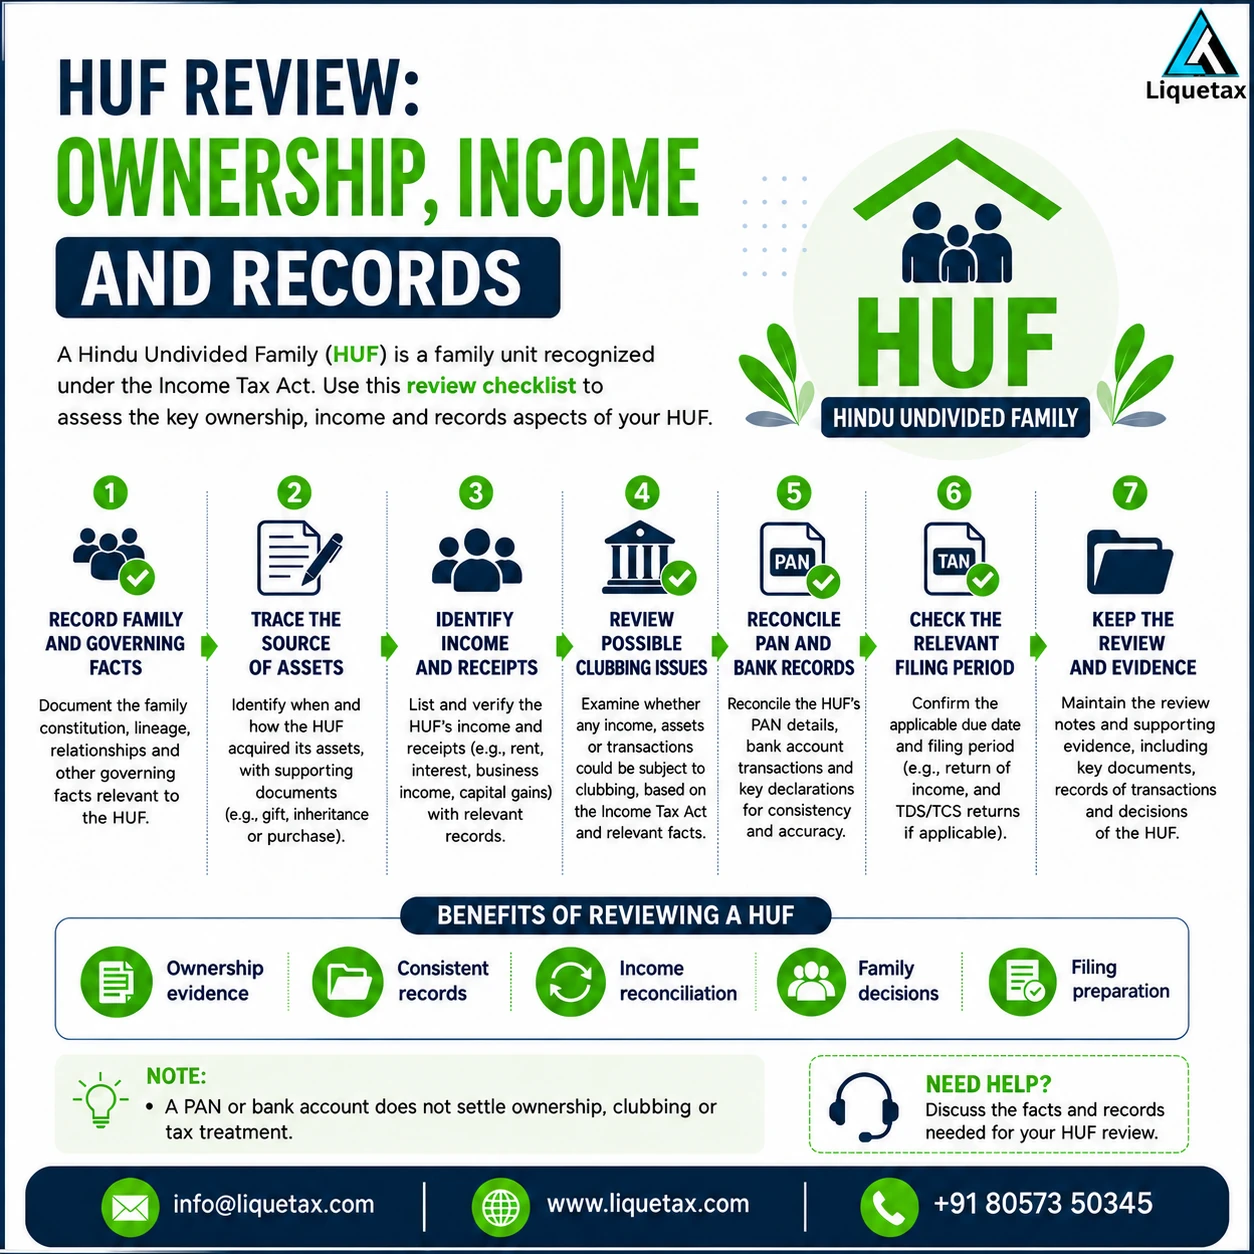
An HUF is not simply a business name that any group can register to divide income. Family and property questions require the actual facts and applicable law. A bank account, declaration or PAN alone does not prove that every asset belongs to the HUF.
Collect the relevant family, succession, property and financial records. If the facts involve a partition, inheritance or disagreement about ownership, seek a suitable legal and tax review together. Do not promise a tax saving before the underlying ownership position has been established.
Trace the source of each asset and receipt
Keep a record of how funds or property came into the HUF and what documents support the transfer or ownership. Distinguish inherited or family property from an individual's personal money and current earnings. The label on a bank transfer does not settle the legal or tax treatment.
If an asset generates rent, interest or business income, connect that income to the asset and its source. Retain agreements, statements and expense records. This helps the reviewer decide whose income should be reported and whether a transfer creates further consequences.
Do not ignore income-clubbing provisions
Transferring or converting personal property to an HUF can still lead to the resulting income being included in the individual's tax computation. The applicable clubbing rules and conditions need review. A transfer that appears tax-free is not automatically a way to shift all later income away from the donor.
For current-period work, consult the Income-tax Act, 2025 framework; earlier returns can involve the preceding Act and assessment-year system. Keep the period explicit. Section numbers or examples from an old article should not be copied into every current calculation without checking the relevant law.
Maintain separate and consistent records
Use suitable banking and accounting arrangements for genuine HUF activity. Keep personal and HUF receipts identifiable, and explain payments made on behalf of family members. A separate ledger is helpful only if it reflects real transactions and ownership.
Review income, eligible deductions, tax credits and the appropriate return conditions for the HUF itself. Do not duplicate a deduction or tax credit already claimed by another person. A complete review should also compare the family's position, rather than show a saving in one return while ignoring another liability.
Plan with the whole family in mind
Ownership rights, family consent, succession and access to funds can be as important as tax. Review how decisions will be made and records maintained. A scheme that looks attractive in a calculator may create practical difficulties if family rights or future changes are not understood.
Ask for an explanation of the facts, applicable framework, clubbing analysis and remaining questions before taking action. No general article can establish your family's ownership or guarantee a saving from transferring a particular asset.
HUF review file
| Record | Question it supports |
|---|---|
| Family and ownership facts | Whether the proposed arrangement is appropriate. |
| Property and succession documents | Source and legal ownership of assets. |
| Transfer and banking evidence | How funds entered the arrangement. |
| Income and expense records | Who should report the resulting income. |
| Earlier returns | Period, credits and any correction questions. |
Illustrative example
Illustrative example: an individual moves personal investment money to an HUF account and expects all future interest to be taxed only in the HUF return. The reviewer should trace the source and check clubbing before accepting that assumption. The account name alone does not decide the tax result.
Frequently asked questions
Does an HUF PAN guarantee a tax benefit?
No. Ownership, source of funds, applicable tax rules and the family's full position need review.
Can salary simply be redirected into an HUF?
A bank transfer does not change the nature of personal earnings. Have the actual transaction and reporting obligations checked.
Does a tax-free transfer mean later income is tax-free?
Not necessarily. Clubbing and other conditions can affect whose income is taxable.
Can old section numbers be used for every 2026 period?
Identify the income period and applicable Act first; earlier returns and current tax-year work can use different frameworks.
Should legal ownership be reviewed as well as tax?
Yes. Family rights, property, succession and genuine ownership are central to a suitable arrangement.
Get clarity before your next filing
Bring the records listed above to a LIQUETAX conversation. Ask for the applicable work, documents, responsibilities and fee components in writing before you authorise a submission. Government charges, professional fees and applicable GST should be shown separately.
Book a conversationOfficial references
Check the linked authority for the rule, form and notification that applies to your facts and period. This guide explains preparation and does not record a professional opinion on an individual case.