
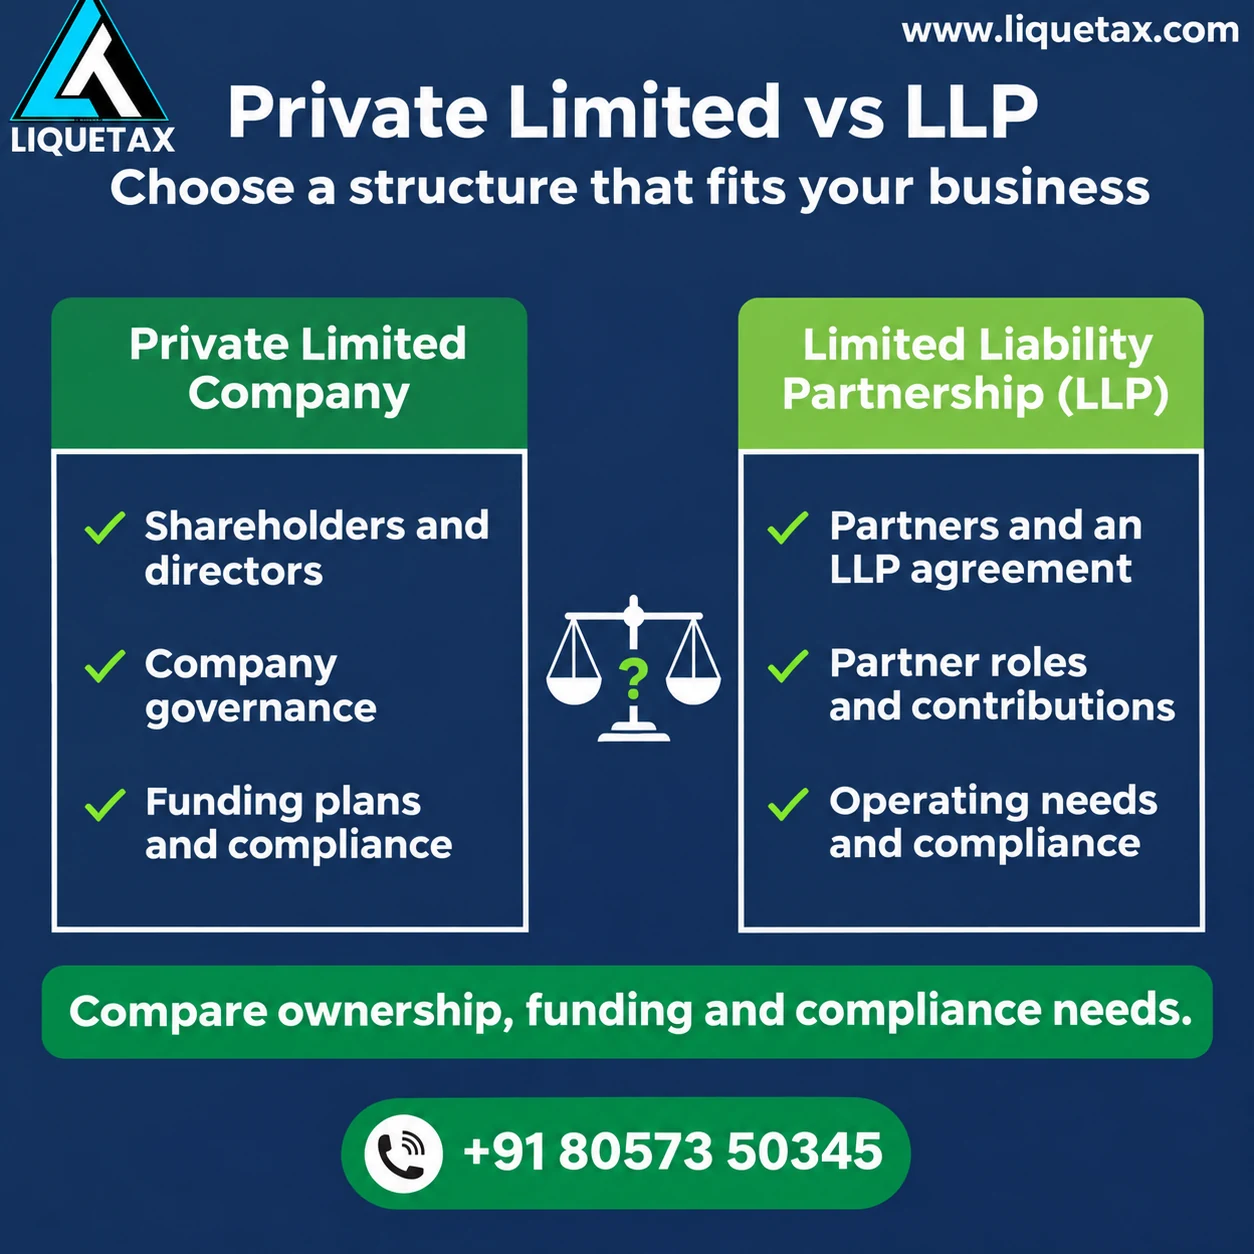
Factors to compare
- Number and role of owners
- Liability and governance expectations
- Funding, profit distribution and continuity plans
STRUCTURE & INCORPORATION
CHOOSE YOUR NEXT STEP
Use a structure comparison before asking for an incorporation quote.
Turn an agreed structure into consistent application records.
A charitable purpose needs a separate governance and formation discussion.
Plan applicable workplace preparation as hiring begins.
Connect the setup decision with accounts, invoicing and customer readiness.
Content updated . Individual guides retain their own source and review information.
WHO THIS HUB HELPS
DECISION SUPPORT
You may not need this route when: An existing entity that only needs a filing, tax registration or event-based change should start with the relevant compliance or tax hub instead.
COMPARE YOUR STARTING POINT
Use these questions to frame an enquiry, not to decide statutory eligibility. Follow the service guide that matches the work you need.
| Your situation | Facts to compare | Next guide |
|---|---|---|
| Cofounders planning investment | Ownership split, funding plans, decision rights and the ongoing company administration you can maintain. | Private limited company preparation → |
| A partner-led practice or business | Partner roles, capital, profit sharing, exit arrangements and the obligations of the proposed structure. | Explore the LLP route → |
| One person starting a business | Whether a company is needed, applicant eligibility, continuity plans and the difference from operating personally. | Consider a one person company → |
SERVICE PATHS
EDUCATIONAL READING
These explain a related question; they are separate from a service engagement. Check each guide's scope, source information and dates before relying on it.
HOW TO AGREE THE WORK
Share your business activity, present stage and the work you need help with.
Confirm the work, fees, review responsibility and follow-up included in the engagement.
Organise the agreed documents, check the details and identify anything still missing.
Check the prepared work before authorising the next step, then retain the agreed handover records.
COMMON QUESTIONS
No. Ownership, liability, funding and ongoing compliance expectations should be compared before choosing.
They should be reviewed against the activity, turnover, location and transaction model; not every registration applies automatically.
Record proposed ownership, contributions, decision rights, profit expectations and exit plans. Use those facts to compare structures and ask which governance and ongoing filing responsibilities each option creates.
Prepare the number and residency of owners, proposed activity, operating state, funding plans and expected administration budget. Compare how each structure handles ownership, liability, decision-making and ongoing work. The cheapest setup quote alone does not settle that decision.